Indonesia holds export dollars onshore for a year, with five permitted uses
Written by

Huan koh
Published on
October 19, 2026

Copy link
Link copied!


Natural resource exporters must place all their proceeds in a state bank for twelve months. The rule restricts the money rather than freezing it, and it has changed four times in nineteen months. An exporter of Indonesian coal, palm oil, nickel or frozen shrimp must now bring the whole of its foreign currency proceeds into the Indonesian banking system. Those proceeds must then stay there for a year. The obligation runs from the export declaration. The money has to land by the end of the third month after the month of that declaration. Since June 2026 it has to sit at a state-owned foreign exchange bank rather than any licensed one. The common description of this is that Indonesia has locked up exporters' dollars. That is not quite what the rule does, and the difference is worth money. Five categories of spending reduce the amount an exporter has to leave on deposit. The funds can also be pledged as security for rupiah credit. Half the proceeds can be converted to rupiah each month. A twelve month placement carries a nil final tax rate, where a one month placement would be taxed at ten per cent. What is genuinely difficult about the rule is not its severity. It is the pace of change. The rule was rewritten in February 2025, in February 2026, in June 2026 and again in September 2026. A treasurer cannot plan a year of working capital against a regulation that moves twice a year. This article sets out the position as at October 2026, what is permitted inside it, and the much larger change that arrived alongside it.
The rule covers four sectors and starts at USD 250,000 per declaration
The retention requirement applies to export proceeds from mining, plantations, forestry and fisheries. It also covers goods processed from those inputs. Scope is set by tariff line rather than by description. An exporter therefore has to check its own tariff codes rather than reason from the name of its sector. The current list runs to more than a thousand lines across mining, plantations and forestry alone.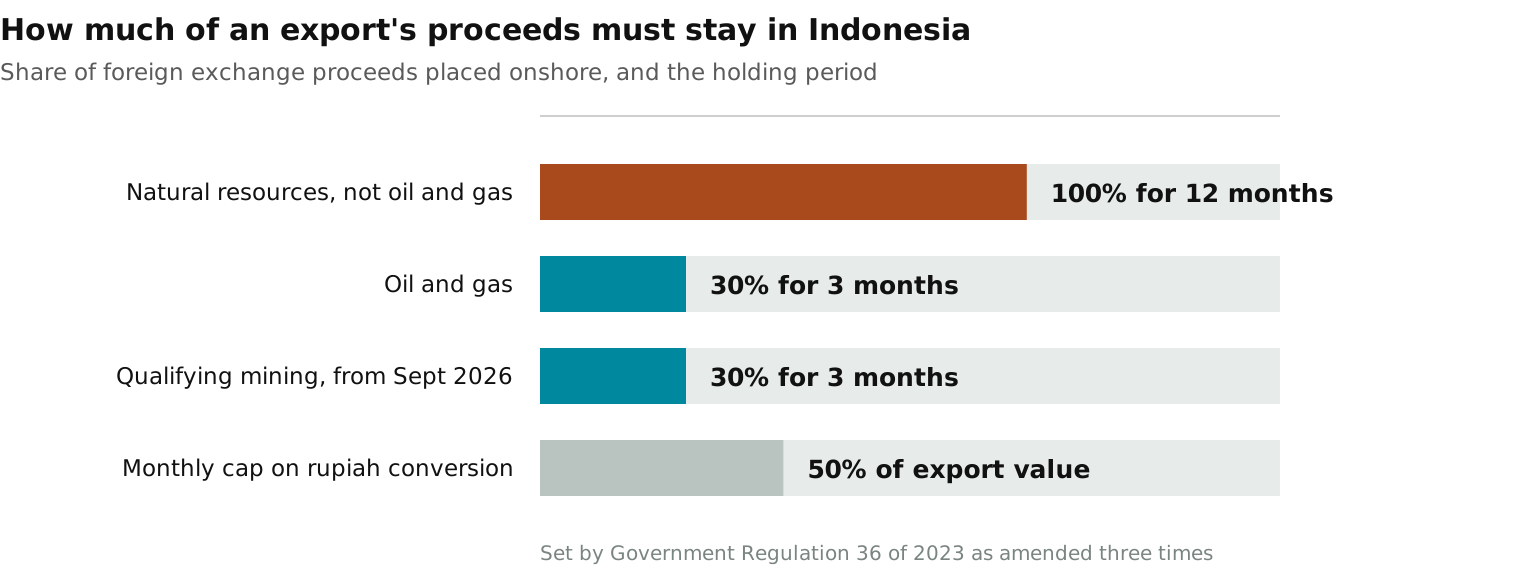 The threshold is the detail most often reported wrongly. The obligation bites at USD 250,000 per export customs declaration. It does not apply per exporter or per year. A trader sending many small consignments can therefore fall outside the rule entirely. A single large shipment brings the full requirement. The voluntary scheme that once allowed smaller exporters to opt in was removed in March 2025.
Oil and gas exporters are not exempt, and the claim that they are is wrong. They retain thirty per cent for three months rather than everything for twelve. The relevant tariff lines are listed in the same decree. From September 2026 a group of qualifying mining exporters moved to the same thirty per cent for three months. That change is dealt with further below.
Five uses reduce what has to be left on deposit
The regulation sets out what the retained proceeds may be spent on. Amounts spent that way reduce the placement obligation rather than breaching it. The permitted uses are government and tax obligations, dividends paid in foreign currency, and procurement of materials, capital goods and services in foreign currency. The fourth is repayment of foreign currency loans. The fifth is conversion to rupiah, up to half the export value each month. The procurement limb is wider than most summaries allow. Bank Indonesia has confirmed in its published guidance that this spending is not confined to goods unavailable domestically. The loan repayment limb covers working capital borrowing and not only capital goods finance. An exporter with foreign currency input costs and foreign currency debt may therefore find that very little is actually left idle.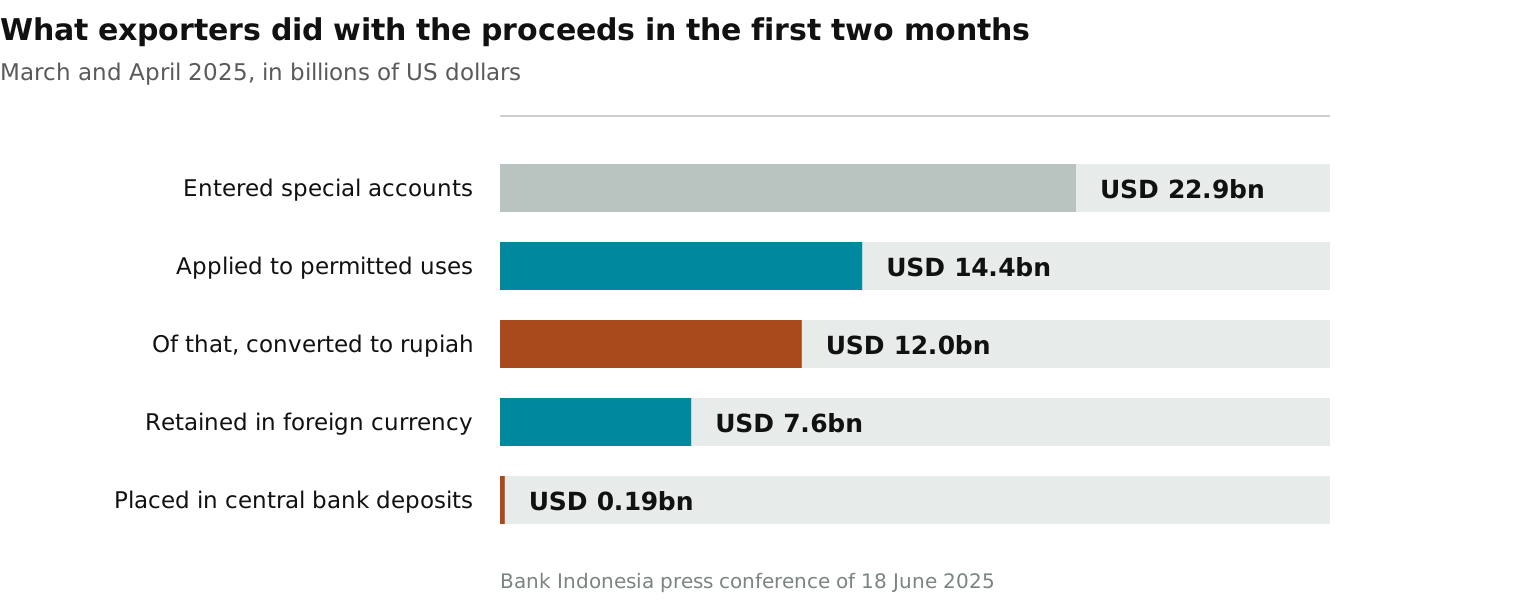 One published breakdown shows how exporters behaved under the rule. USD 22.9 billion entered special accounts in March and April 2025. Exporters applied USD 14.4 billion of that to permitted uses and retained USD 7.6 billion in foreign currency. Of the amount applied, USD 12 billion was converted into rupiah. Only USD 194 million reached foreign currency term deposits at the central bank.
Proceeds can secure a rupiah loan but not a dollar one
The collateral rules are specific, and the distinction matters commercially. Retained proceeds may be pledged as security for rupiah credit. The regulator has stated that pledging does not affect the bank's gearing calculation. They may not be pledged for a foreign currency loan. The facility is capped at the amount pledged, a written declaration is required, and a default does not extinguish the placement obligation. Foreign exchange swaps are permitted on the buy side only. The swap must be done at the bank holding the placement. The proceeds must return to the originating foreign currency account. The tenor must fall inside the remaining placement period. Sell-side swaps and linked forwards are not available. The placement itself can sit in a special account, a term deposit at a state bank, central bank instruments, or government securities bought in the primary market. This is the point exporters have pressed hardest in public. In May 2026 the chairman of the advisory council at the Indonesian mining professionals association put the complaint plainly. The money is there, he said, but the business has to borrow it back at a higher rate than the deposit pays. That is a cost of capital argument rather than a liquidity one. It is also the honest version of the grievance.Export services have been suspended, and the enforcement record is public
There is a single sanction, and it is a serious one for a trading business. The Minister of Finance may suspend an exporter's access to export services, which customs then executes. There is no fine on the exporter. The suspension does not remove the underlying obligation. Bank Indonesia supervises the inflow and the placement, and the financial services authority supervises the accounts themselves.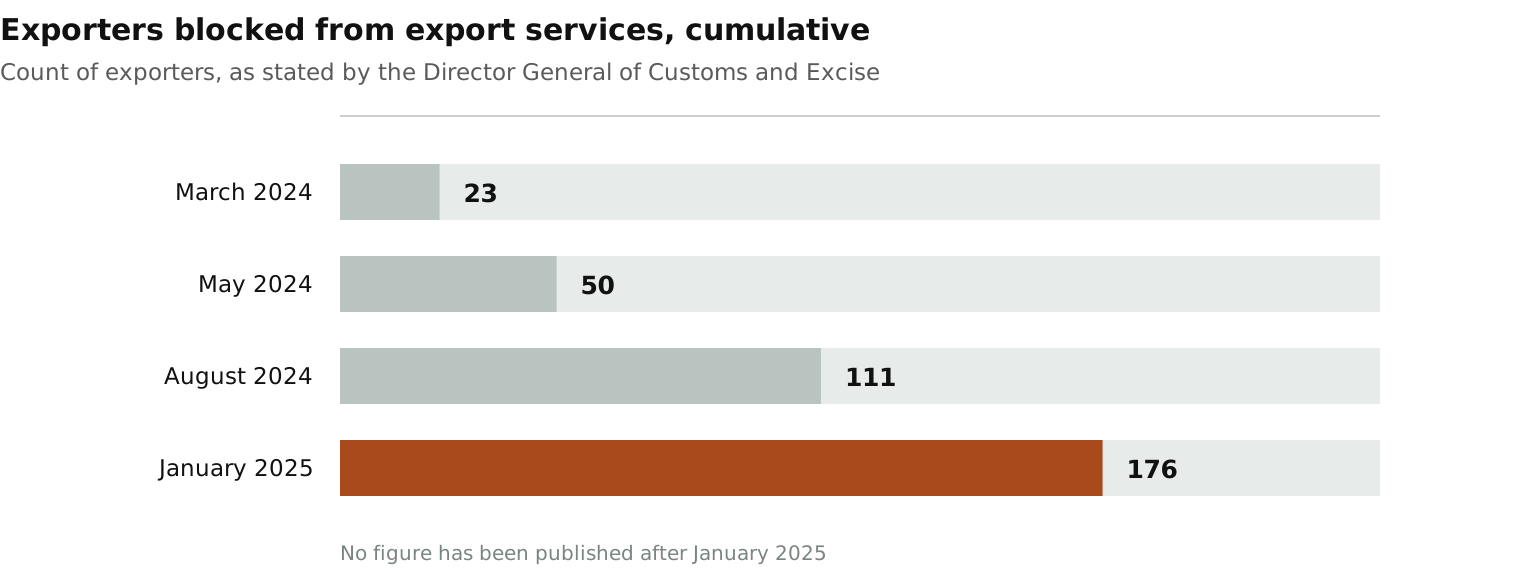 The enforcement has happened. The cumulative number of exporters blocked rose from 23 in March 2024 to 176 by January 2025. Some of those were unblocked after remediation. All of that enforcement relates to the earlier thirty per cent requirement rather than the current one. No count has been published since January 2025, which means the current rate of enforcement is unknown rather than low.
Sixty four mining exporters returned to thirty per cent in September 2026
The government has given ground in stages, and the most recent concession is narrow but real. From September 2026 a defined group of mining exporters may retain thirty per cent for three months. They may do so at any of fifteen designated banks, five of them state-owned and ten of them not. The criteria require an Indonesian company in mining with a shareholder of at least ten per cent from a partner country. The partner countries are the United States, China, Hong Kong, Australia and Canada. Of 537 registered mining exporters, 64 qualify, which is about twelve per cent. An eligible exporter has five working days to opt out in writing, and silence counts as acceptance. The choice is irreversible and applies to everything the company exports. The list is reissued every month.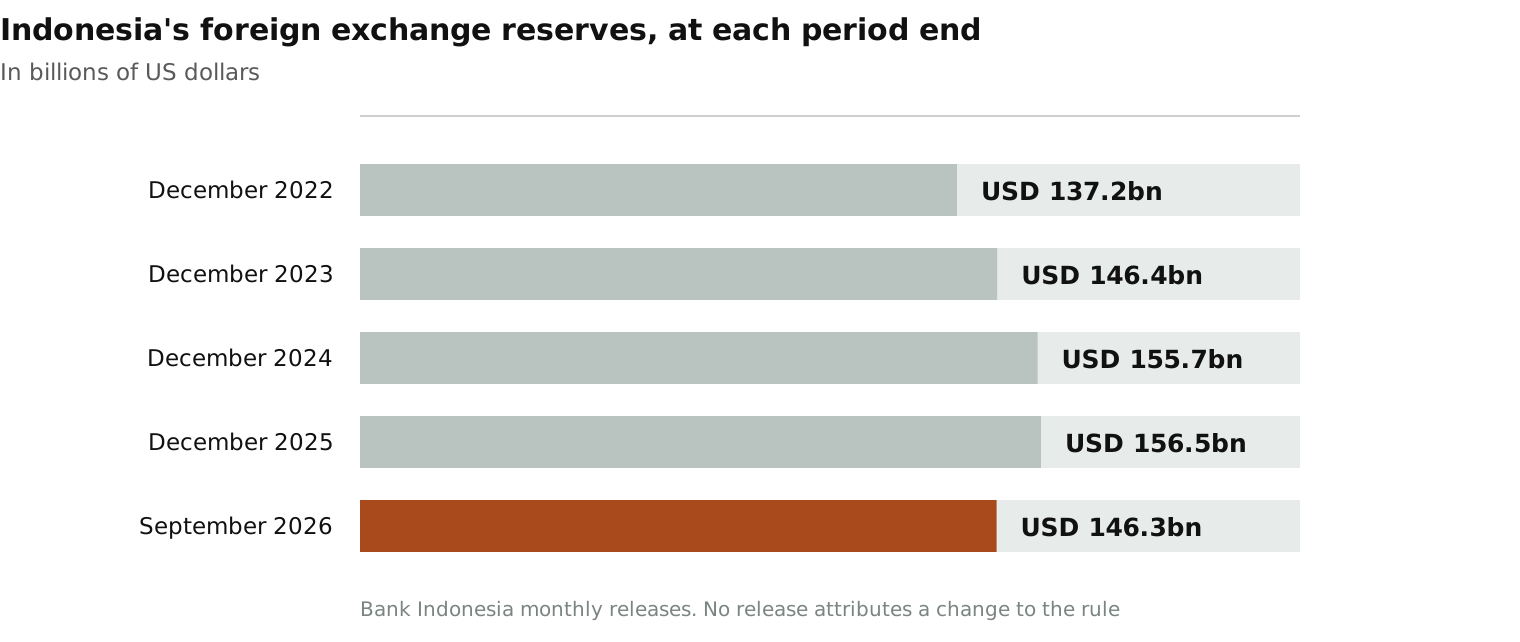 Whether the rule has achieved its stated aim is not settled by the reserve figures. Reserves stood at USD 156.5 billion at the end of December 2025. They stood at USD 146.3 billion at the end of September 2026. They are therefore lower after the rule than before it. Bank Indonesia's own releases do not mention the retention scheme at all. If the objective is domestic dollar liquidity and rupiah demand, which is what officials actually say, the evidence is better.
The rupiah leg cannot leave the country at all
Three restrictions compound, and the second is the least discussed. The proceeds are held onshore at a state bank for a year. The rupiah created by conversion cannot then be transferred abroad. Indonesia maintains a prohibition on moving rupiah out of the country, alongside bans on offshore rupiah forwards and on rupiah credit to non-residents. Conversion is therefore a one-way movement into the domestic economy. The daily and monthly rupiah transfer limits quoted in many summaries come from a 2016 regulation. That regulation was revoked in July 2022, and those figures should not be cited as current law. The current thresholds are not published. Outbound foreign currency transfers must carry the value, the purpose and the parties. They must also state the financial relationship between the parties, with supporting documents required above a threshold that is also unpublished. Offshore borrowing has its own regime. An annual loan plan falls due in the middle of March each year, and monthly reporting on the fifteenth. A credit rating report is required. Non-revolving drawdowns must pass through an Indonesian foreign exchange bank. A drawdown outside one attracts a sanction of a quarter of a per cent of the amount, capped in rupiah. Late reporting is charged daily, and persistent failure is notified to the parent company and the creditor.A state company becomes the only exporter of coal and palm oil
For a trading business the larger change is not the retention rule at all. From June 2026 exports of strategic natural resources are routed exclusively through a state export entity. That entity acts as sole exporter and can set the price. The first commodities named are coal, palm oil and ferro alloy. All palm oil derivative exports must go through it after 31 December 2026, with full implementation from 1 January 2027. That changes the question. The retention rule asks what an exporter may do with its proceeds. The single gate asks whether a private trader can be the exporter of record at all. Any structuring work for Indonesian natural resource trade done in late 2026 that ignores the second question is answering the wrong one.Singapore has had no exchange control since 1978
Singapore has no retention requirement and no surrender requirement. There is no repatriation percentage, no holding period, no designated bank and no conversion cap. That is not a recent liberalisation. A Monetary Authority of Singapore notice issued on 25 May 1978 exempted all persons from the obligations imposed under the Exchange Control Act. It took effect on 1 June 1978. It removed exchange control formalities for all payments and capital transfers, and abolished the statistical returns that went with them. What Singapore does require is corporate rather than monetary. A company holds an annual general meeting and files an annual return within seven months of its financial year end. Late filing carries a penalty. An audit is required where the company exceeds two of three thresholds for revenue, assets and headcount. Tax is assessed at seventeen per cent. An estimate of chargeable income is due within three months of year end, and the return by the end of November. A trading company receiving its own export proceeds does not need a payment services licence in Singapore. The licensing requirement attaches to the business of providing a transfer service to other people. A company moving its own money provides a service to nobody. One residual currency measure remains in place, and it concerns Singapore dollar lending to non-resident financial institutions. It is addressed to banks rather than to exporters.| Position | Indonesian retention rule | Singapore company |
|---|---|---|
| Proceeds of an Indonesian export | Reached in full, by tariff line | Reached, because the export is Indonesian |
| Where proceeds must first land | Indonesian state bank, within three months | Does not change the landing requirement |
| Holding period | Twelve months, or three for oil and gas | Does not shorten the period |
| Foreign currency procurement | Permitted, reduces the obligation | Can be the counterparty, if genuine |
| Dividends in foreign currency | Permitted, reduces the obligation | Can be the recipient |
| Repayment of a foreign currency loan | Permitted, reduces the obligation | Can be the lender, with reporting |
| Third country sale at a low price | The rule exists partly to address this | Priced by transfer pricing rules |
| Proceeds of a non-Indonesian trade | Not reached | No retention requirement at all |
The rule has a rationale, and predictability is the fair criticism
Indonesia exported USD 282.91 billion of goods in 2025. It held USD 146.3 billion of reserves at the end of September 2026. A country exporting at that scale while holding that level of reserves has a real structural question. Five months of import cover is also thinner than it looks. The misinvoicing concern is also substantive rather than rhetorical. A review of about 6,500 declarations worth more than USD 14 billion produced a preliminary estimate of around USD 5 billion a year in understated value. The government was explicit that this is not additional money already earned abroad. Structures in which an Indonesian exporter sells cheaply to a related offshore trader are a real leakage. A Singapore firm should say so rather than pretend otherwise. The rule is also not confiscatory in design. The exporter keeps the money and earns a return on it. A twelve month placement pays nil final tax, against up to twenty per cent on ordinary investment income. The proceeds may be spent on five categories, pledged for rupiah credit without a gearing consequence, and used in buy-side swaps. The government has visibly responded to representations at each revision. Two criticisms survive that. The first is predictability rather than severity, and it is the stronger point. The rule changed four times in nineteen months. The eligible bank universe was narrowed and then partly reopened. The qualifying mining list republishes every month with a five day opt-out. Working capital cannot be planned against that. The second concerns the state bank limb specifically. A dollar held at a foreign-owned bank incorporated in Indonesia is inside the Indonesian financial system exactly as much as a dollar at a state bank. That limb has no evident monetary justification. The September 2026 concession reopened ten non-state banks for 64 exporters, which rather concedes the point.What this means for exporters, treasurers and advisers
For an Indonesian exporter, the first task is mechanical, and nobody can do it from a summary. The tariff codes of every line actually exported determine whether the rule applies. The USD 250,000 test then applies declaration by declaration. The second task is to map foreign currency outflows against the five permitted uses. Every dollar of genuine foreign currency procurement, dividend or loan repayment reduces the placement obligation rather than breaching it. For a treasurer running a regional group, the planning assumption should be that the Indonesian limb is slow and the rest of the group is not. Proceeds of an Indonesian export are reached wherever the group sits. The useful work is therefore sequencing rather than relocation. A Singapore company genuinely supplying inputs, genuinely lending, or genuinely receiving dividends is a permitted counterparty under the regulation itself. That is a better footing than a structure the rule was written to catch. For an adviser, two warnings are worth passing on. The published scans of the 2026 amendments are poor quality, with percentages mangled by character recognition. Any figure quoted in a contract should therefore come from the gazette rather than a downloaded copy. The guidance on moving retained proceeds abroad for permitted procurement is also internally inconsistent. Indonesian counsel should settle that question before anybody commits in writing.Our blog
Latest blog posts
Tools and strategies modern teams need to help their companies grow.