A Singapore company defers a Canadian owner’s tax. It does not reduce it.
Written by

Huan koh
Published on
September 22, 2026

Copy link
Link copied!


Active business income escapes annual attribution. The bill arrives on repatriation, at full marginal rates. Consider a Canadian resident in his forties. He owns a fast-moving consumer goods wholesale and distribution business in Ontario. He buys branded household and personal care lines from third-party suppliers, and sells them to retailers and regional distributors. Demand from Southeast Asia has grown to the point where he wants a regional base. He is weighing Singapore against Dubai and Hong Kong. The scenario that follows is a composite rather than a client. The question he asks first is whether a Singapore company lowers what he personally pays. The short answer is that it postpones Canadian tax rather than reducing it. Under one common structure it increases the total. The reason sits in two provisions of Canada's Income Tax Act that most offshore marketing material leaves out.
What Canada taxes, and at what rate
Canada taxes its residents on worldwide income. Residence is a question of fact, weighed on the whole of a person's circumstances. The Canada Revenue Agency treats three ties as almost always significant. Those are a dwelling in Canada, a spouse or common-law partner in Canada, and dependants in Canada. Secondary ties are assessed together rather than one by one. Separately, an individual who is not otherwise resident but spends 183 days or more in Canada in a calendar year is deemed resident for that whole year.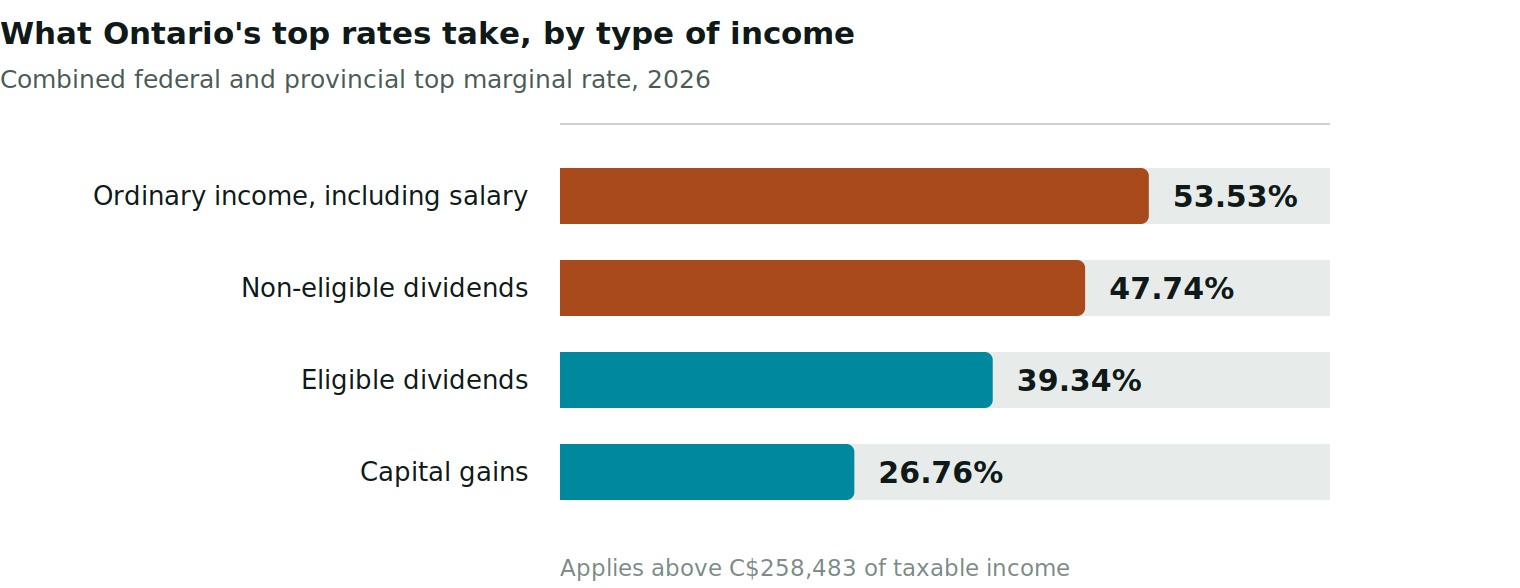 For 2026 the federal rate runs from 14% on the first C$58,523 of taxable income to 33% above C$258,482. Provincial tax sits on top of that. The combined top marginal rate on ordinary income is 53.53% in Ontario, 53.50% in British Columbia and 53.31% in Quebec. Alberta stops at 48.00%. Newfoundland and Labrador reaches 54.80%, but only above C$1,141,276. That makes it the wrong comparison for most owner-managers.
One widely repeated figure is now out of date. The proposed increase in the capital gains inclusion rate from one-half to two-thirds was deferred in January 2025. It was then cancelled on 21 March 2025. The measure was never enacted, so no repealing legislation was needed. The inclusion rate for 2026 is one-half. That puts the top capital gains rate at 26.76% in Ontario, exactly half the ordinary-income rate.
Reducing the Canadian bill before any offshore structure
Most of the available reduction sits inside Canada, and it is unglamorous. The small business deduction taxes the first C$500,000 of active business income at a combined 12.2% in Ontario, for a year ending before 1 July 2026. Ontario cut its lower rate on that date. The combined rate falls to roughly 11.7% blended for calendar 2026, and 11.2% from 2027. Two grinds erode the deduction. The limit reduces on a straight line where taxable capital employed in Canada exceeds C$10 million, and disappears at C$50 million. It also falls by C$5 for every C$1 of adjusted aggregate investment income above C$50,000, reaching nil at C$150,000. The lifetime capital gains exemption is the largest single item. It stands at C$1,275,000 for 2026. It had been fixed at C$1.25 million for dispositions from 25 June 2024, before indexation resumed. It applies to qualified small business corporation shares, and it is not automatic. At disposition, 90% or more of the company's asset value must be used principally in an active business carried on primarily in Canada. Throughout the preceding 24 months, more than half must have been. A distributor holding surplus cash, guaranteed investment certificates or non-operating property can fail the first test. The 24-month look-back means cleaning that up takes planning rather than a signature. Two related points. The Canadian Entrepreneurs' Incentive announced in Budget 2024 is not proceeding. Budget 2025 confirmed that by omission on 4 November 2025, so it should not appear in any plan. Separately, the tax on split income restricts paying dividends to family members at their own rates. The excluded shares route out of it is more available to this business than to a professional practice. It requires an individual aged 25 or over to hold, directly, 10% or more of both the votes and the value. The corporation must earn less than 90% of its income from services, and must not be a professional corporation. A goods wholesaler meets those last two conditions. Shares held through a family trust or a holding company fail the first.Why the Singapore company defers rather than reduces
A Singapore company wholly owned by a Canadian resident is a controlled foreign affiliate. Its income is tested against the foreign accrual property income rules. Those rules attribute certain income to the Canadian shareholder each year, whether or not it is distributed. Income from a genuine active business is not in that base at all. It is excluded structurally rather than by exemption, so a real distribution business earns real deferral. Passive income is treated differently. Interest on the Singapore company's cash balances, and foreign exchange gains on non-business holdings, are attributed annually. That point is routinely missed.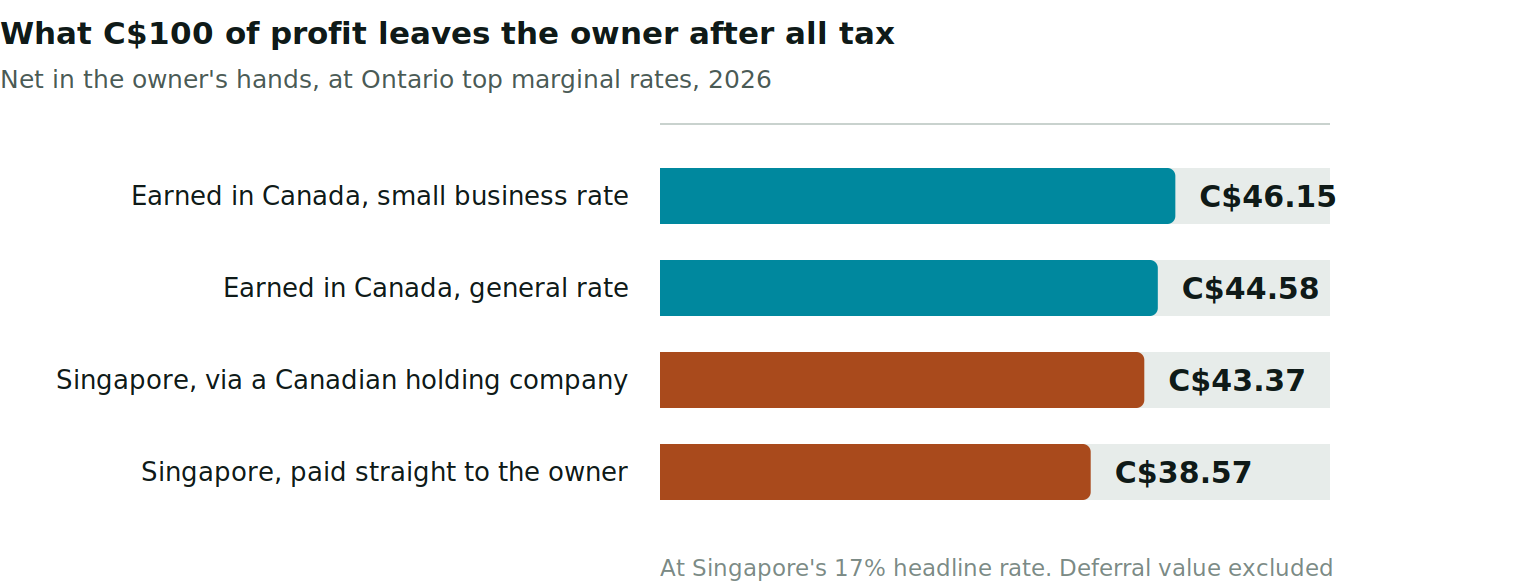 The deferral ends at repatriation, and that is where the structure disappoints. A dividend from a non-resident corporation to a Canadian individual is included in income at 100%, as ordinary income. There is no gross-up and no dividend tax credit. Both apply only to dividends from corporations resident in Canada. There is no deduction for the underlying Singapore corporate tax either, because the mechanism that provides one is open only to a corporation resident in Canada. And Singapore does not withhold on dividends, so there is no foreign tax credit to claim.
The arithmetic follows. C$100 of profit taxed in Singapore at 17% leaves C$83. Paid straight to the owner and taxed at Ontario's 53.53%, it leaves C$38.57. The same C$100 earned in Canada at the small business rate and then distributed leaves C$46.15. At the general rate it leaves C$44.58. On repatriated profits the Singapore company is the worst of the three outcomes, not the best.
What a Canadian holding company changes
The provision that fixes this is section 113 of the Income Tax Act. It is restricted on its face to a corporation resident in Canada. Active business earnings of a foreign affiliate accumulate as exempt surplus, provided the affiliate is resident in a country with which Canada has a comprehensive tax treaty. Singapore qualifies, on a convention signed on 6 March 1976. A dividend paid out of that exempt surplus to a Canadian holding company attracts a full offsetting deduction. It therefore arrives free of Canadian corporate tax. Inserting that holding company lifts the same C$100 from C$38.57 to C$43.37 in the owner's hands. It also preserves the deferral until he chooses to take money personally. It still does not beat earning the profit in Canada on tax alone. What it does is let the Singapore company stand on its commercial merits, without an avoidable tax penalty attached. The difference between the two Singapore routes is roughly 12% of after-tax cash. It comes entirely from the presence or absence of a Canadian company in the chain.The three ways the structure fails outright
The first failure is residence. A company incorporated outside Canada is resident in Canada if its central management and control is exercised there. Canada's deemed-residence rule for corporations covers only companies incorporated in Canada. A Singapore company is therefore tested at common law, and the authorities look at where decisions are actually taken rather than where board minutes say they were. A sole shareholder who is also the controlling director, deciding from Ontario, produces a Canadian-resident company. The Canada–Singapore treaty does not rescue this. Its tie-breaker for companies asks the two tax authorities to try to agree, rather than deciding the question. Singapore applies the same control and management test for its own residence, so the same facts can also cost the company its Singapore treaty access. The second is the supply chain. A specific rule recharacterises income from the sale of property as attributed income. It bites where the cost of that property is relevant in computing income from a business carried on in Canada, and where the goods were not produced in the affiliate's own country. A safe harbour applies where more than 90% of the affiliate's sales revenue comes from arm's-length customers. A Singapore company buying from unrelated suppliers and selling to unrelated Asian customers, with no Canadian operating company on either side, is generally outside the rule. A Singapore company that buys from or sells to the Canadian business is the classic failure case. It also brings Canada's transfer pricing rules with it. Those rules were rewritten for taxation years beginning after 4 November 2025, and the deadline to produce documentation on request fell from three months to 30 days. The third is reporting. Shares of the Singapore company are specified foreign property. The exclusion for property used in an active business does not cover them. A foreign affiliate information return is due within 10 months of the year end. Penalties run to C$2,500 for simple failure, and to C$12,000 where the failure is knowing or grossly negligent. Those double where a demand to file has been served. The general anti-avoidance rule was also tightened for transactions after 2023. It now carries a 25% penalty on the denied benefit, and an economic substance test that counts against structures with little real activity.Singapore, Dubai and Hong Kong compared
The comparison is closer than it is usually presented, and Singapore does not win every line. Two of the three offer a lower headline rate. One of the three charges no tax on goods at the border and no consumption tax at all. What separates them is less the rate than what has to be true, and stay true, for that rate to hold.| Condition | Singapore | United Arab Emirates | Hong Kong |
|---|---|---|---|
| Headline corporate rate | 17% | 9% above AED 375,000 | 16.5%, or 8.25% on the first HK$2m |
| Rate a distributor can actually reach | 17%, reduced by exemptions | 0% only inside a Designated Zone | 16.5% unless an offshore claim succeeds |
| Canada treaty on dividends | 15% | 5% at a 10% holding | 5% at a 10% holding |
| Treaty agreement with Canada | CPTPP, in force 30 December 2018 | Negotiations concluded 24 July 2026 | None |
| Member of RCEP | Yes | No | Applicant since January 2022 |
| Import duty on general goods | None | 5% on clearance to the mainland | None |
| Value added on goods and services tax | 9% | 5% | None |
| What must be sustained | Control and management in Singapore | Designated Zone substance and routing | An all-or-nothing offshore claim |
Where the Singapore case is weakest
On the Canadian treaty, Singapore is the worst of the three. The convention dates from 1976. It caps dividends at a flat 15%, with no reduced rate for a substantial shareholding. Both the UAE and Hong Kong treaties give 5% to a company controlling 10% or more of the voting power. Both also give 10% rather than 15% on interest and royalties. Singapore levies no dividend withholding tax of its own, so the practical bite falls on Canadian-source payments. The treaty text is still what it is. The UAE headline of 9% is genuinely lower, and the free zone rate of 0% is real. It is much harder to reach than the marketing suggests. Distribution qualifies only where it is conducted in or from a Designated Zone. That is a fenced, customs-controlled area on a specific Cabinet list. Goods entering the country must also be imported through that zone. Most free zones sold to foreign owners are not Designated Zones. Finished consumer goods are not qualifying commodities either, so that separate route is closed. And non-qualifying revenue above the lower of AED 5 million or 5% of turnover costs the status entirely, rather than taxing the excess. Hong Kong's difficulty is different and sharper. Its territorial system exempts foreign-sourced profits. But for trading profits the tax authority's practice is all or nothing. Where either the purchase or the sale contract is effected in Hong Kong, the presumption is full taxability, and apportionment does not apply to trading profits. A distributor with a Hong Kong office, Hong Kong staff taking orders and Hong Kong trade finance will struggle to keep an offshore claim standing. The substance needed to sustain that claim also pulls against the substance needed to obtain a Hong Kong residence certificate for treaty purposes.What Singapore actually offers a goods business
Singapore's advantage is not the headline rate. It is that the rate is predictable, and requires no claim to be sustained year after year. A distributor in Singapore pays a known percentage and files a return. A distributor relying on a Hong Kong offshore claim, or on qualifying free zone status in the UAE, is defending a position annually. The cost of losing that argument is the whole benefit, not a portion of it.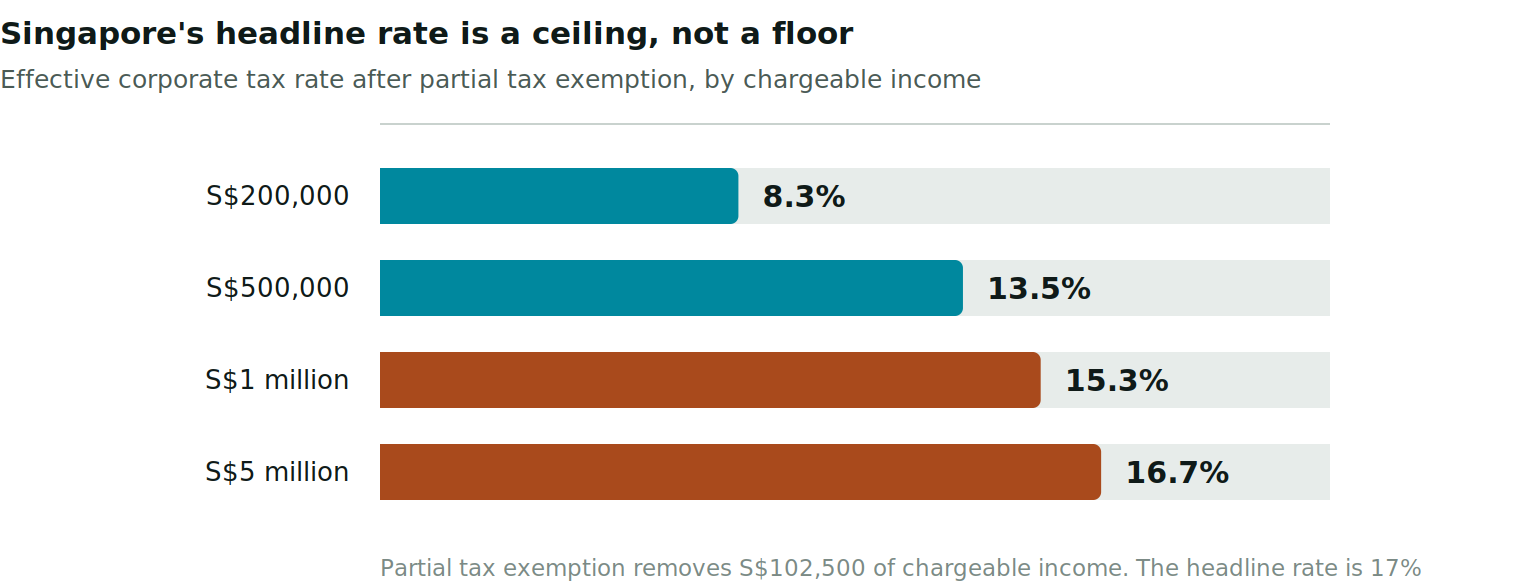 Partial tax exemption removes S$102,500 of chargeable income. That puts the effective rate at 8.3% on S$200,000 of profit, 13.5% on S$500,000 and 15.3% on S$1 million. A 50% corporate tax rebate for the 2026 year of assessment reduces it further. That rebate is capped at S$40,000 and was announced on 7 April 2026. A newly incorporated company meeting the shareholder conditions can also claim a larger start-up exemption for its first three years.
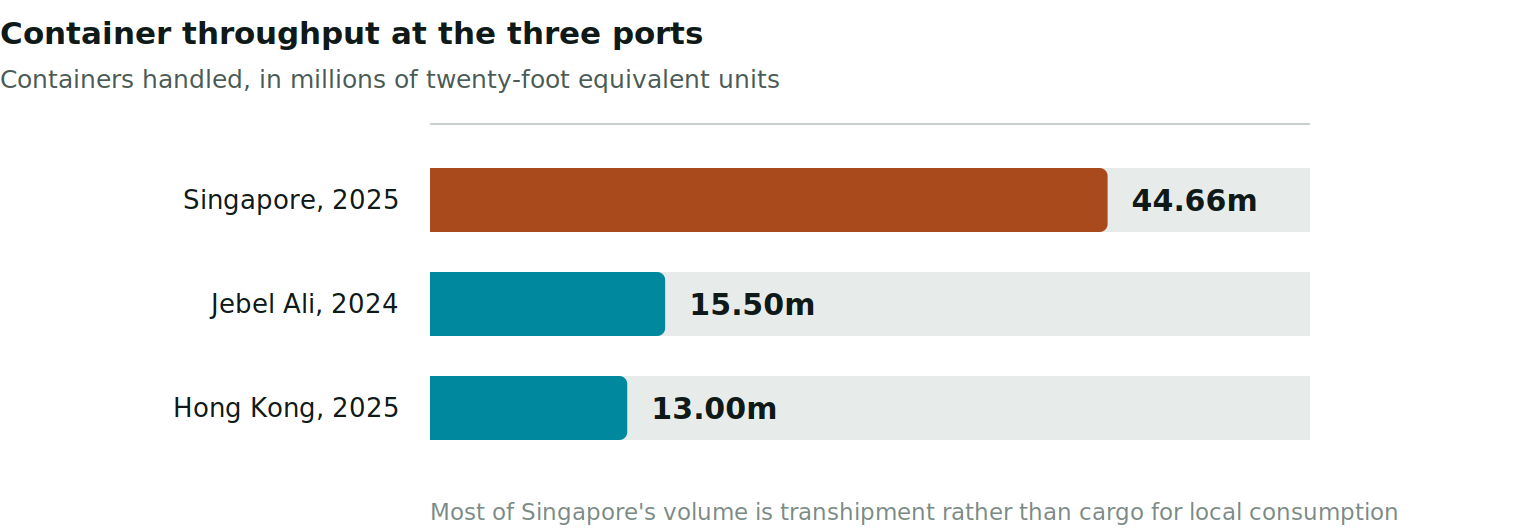 On the trade side, Singapore is the only one of the three that shares an agreement with Canada. Both are original parties to the Comprehensive and Progressive Agreement for Trans-Pacific Partnership, in force for both since 30 December 2018. Singapore is also a member of the Regional Comprehensive Economic Partnership. Hong Kong applied to join that agreement in January 2022, and an accession working group was approved on 21 September 2026. That is a procedural step rather than membership. Canada and the UAE concluded negotiations on a partnership agreement on 24 July 2026, with no signature or implementation date announced.
One caution on trade agreements. Preferential treatment attaches to goods that meet the rules of origin, not to the company that invoices them. A Singapore entity buying third-country goods and reselling them does not make those goods originating. The value lies elsewhere. It sits in preferential access for Canadian-origin and Singapore-origin goods, and in the regional cumulation rules that Singapore can use and Hong Kong currently cannot.
On banking, no jurisdiction publishes verifiable data on account opening outcomes for foreign-owned trading companies. That applies to the Monetary Authority of Singapore, the Hong Kong Monetary Authority and the UAE central bank alike. None publishes approval rates, rejection rates or timelines. Every specific claim of that kind in circulation traces back to marketing material with no published basis, and should be discounted accordingly.
What this means for owners staying in Canada, owners considering a move, and owners with an offshore company already
For an owner who intends to remain Canadian resident, the Singapore company should be justified commercially rather than fiscally. It earns deferral on genuine active business income for as long as profits stay offshore. That is worth having when the business is reinvesting. It does not reduce the eventual personal bill. Paid directly to the individual, it costs more than earning the same profit in Canada. If the company is going ahead, a Canadian holding company between the owner and the Singapore entity is what makes the arithmetic behave. That decision is cheapest to take at the outset, rather than by reorganising later. For an owner considering leaving Canada, the departure charge is the number to establish first. Ceasing Canadian residence triggers a deemed disposition of most capital property at fair market value. The shares of the Canadian operating company are caught by it. Canadian real property and business property held through a Canadian permanent establishment are excluded, as are registered plans. Payment can be deferred without interest by election. Security is required where the federal tax on the deemed disposition exceeds C$16,500. That figure should be quantified before any move is planned. It is usually the largest single item, and it does not go away by leaving quietly. For an owner who already runs goods through an offshore company, three checks are worth making this quarter. Establish where board decisions are actually taken, and whether the record supports it, because the residence test looks at conduct rather than paperwork. Establish whether any Canadian entity sits on either side of the offshore company in the supply chain. That is what turns trading profit into attributed income, and it brings transfer pricing documentation with a 30-day production deadline. And confirm the foreign affiliate and foreign property returns have been filed. Those penalties accrue whether or not any tax was ever owing.Our blog
Latest blog posts
Tools and strategies modern teams need to help their companies grow.