Singapore eased its family office rules one week after China taxed offshore trusts
Written by

Huan koh
Published on
September 15, 2026

Copy link
Link copied!


For a Hong Kong owner weighing a move, the deciding factor is tax residence rather than nationality. China's Ministry of Finance and State Taxation Administration issued Announcement No. 21 of 2026 on 24 July 2026. It brings offshore trusts into the individual income tax net. It also sets a deadline of 22 October 2026 for historic filings. Seven days later, on 31 July 2026, the Monetary Authority of Singapore issued circular FDD Cir 05/2026. That circular eased several conditions attached to the tax incentives Singapore family offices rely on. The two documents are unrelated. Together they frame the decision now facing a large amount of Hong Kong capital. Consider a Hong Kong business owner in his fifties. He has been a permanent resident since before the 1997 handover, and his manufacturing and distribution company still operates from Kowloon. His assets sit across Hong Kong banks, a British Virgin Islands holding company and property. He wants to move part of that to Singapore. He also intends to sit in the investment meetings himself, alongside a locally hired manager and a resident director who takes part in decisions. The scenario that follows is a composite rather than a client.
What Singapore changed on 1 August 2026
The Monetary Authority of Singapore administers the section 13O and section 13U fund tax exemptions on two separate tracks. A single family office, or SFO, is a firm that manages the assets of one family and no one else. A non-SFO fund is any other qualifying fund. In practice that means a fund run by a third-party fund management company, for investors drawn from outside a single family. From 1 August 2026, a non-SFO fund must also hold third-party capital at the point of application, or show a bona fide intention to raise it. The two tracks carry different entry thresholds. More than 2,000 family offices in Singapore held one of these incentives at the end of 2025. That figure comes from a written parliamentary reply by the MAS chairman.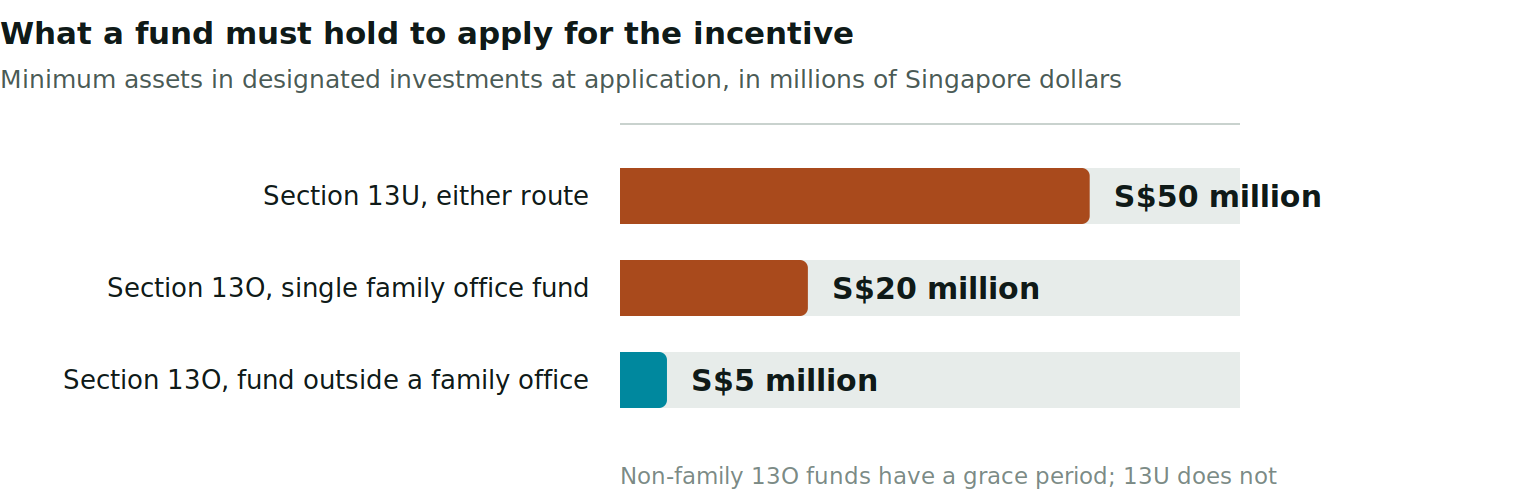 An SFO fund applying under section 13O must hold at least S$20 million in designated investments at the point of application. A non-SFO fund needs S$5 million under the same section. It also gets a grace period, running to its third year of assessment. Section 13U sits at S$50 million on both tracks. It must be met at application, with no grace period. A 13O fund must be a company incorporated in and tax resident in Singapore. A 13U fund may take any legal form, onshore or offshore, provided it is managed from Singapore.
Sections 13O and 13U, before and after
The changes taking effect on 1 August 2026 fall into three groups. The hiring requirement was rephased. The post-award assets test was recast. The cap on physical precious metals was removed altogether.| Condition | 13O before | 13O from 1 Aug 2026 | 13U before | 13U from 1 Aug 2026 |
|---|---|---|---|---|
| Minimum assets in designated investments at application | S$20 million | S$20 million | S$50 million | S$50 million |
| Investment professionals at application | 2 | 1 | 3 | 2 |
| Investment professionals by first financial year end | 2 | 2 | 3 | 3 |
| Assets tested after the award | Throughout the incentive period | At each financial year end | Throughout the incentive period | At each financial year end |
| Physical precious metals as designated investments | Capped at 5% of portfolio | No cap | Capped at 5% of portfolio | No cap |
| Fund vehicle | Singapore-incorporated company | Singapore-incorporated company | Any form, onshore or offshore | Any form, onshore or offshore |
A phased hiring concession for family office funds
The concession on investment professionals moved a deadline rather than a headcount. A 13O fund managed by an SFO may now apply with one qualifying investment professional in place. The second must be employed by the end of the financial year relating to the first year of assessment of the award. A 13U fund may apply with two and must reach three by the same point. The totals of two and three are unchanged. The conditions on those individuals are also unchanged. At least one must come from outside the family. Each must be tax resident in Singapore. Each must spend more than half their time on qualifying investment activity, and be paid more than S$3,500 a month. For the owner in this scenario, the concession removes the step at which family office plans most often stall. That step is recruiting a second professional before the structure exists, and before there are assets for that person to manage.The annual spending floor for an SFO fund
The second condition that determines whether the structure is viable at a given size is local business spending. It is a fixed annual cost, payable whether the portfolio rises or falls.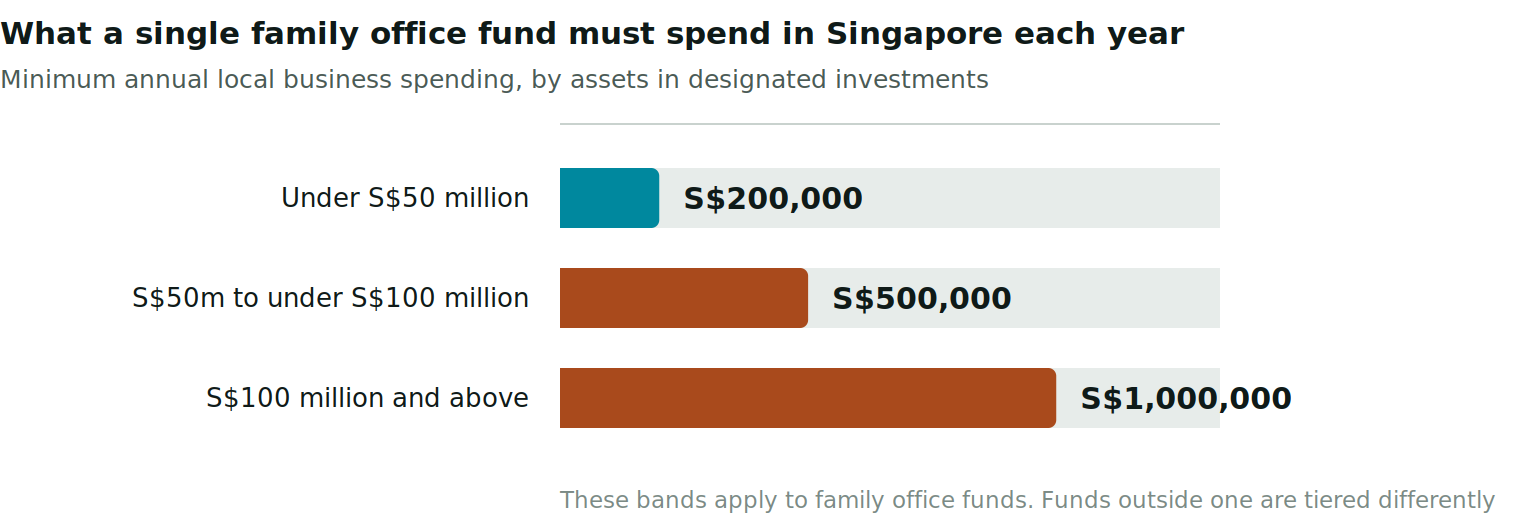 An SFO fund holding under S$50 million in designated investments must spend at least S$200,000 a year in Singapore. Between S$50 million and just under S$100 million, the floor is S$500,000. At S$100 million and above it is S$1 million. The bands for non-SFO funds sit at much larger asset levels and lower amounts. They run from S$200,000 below S$250 million to S$500,000 at S$2 billion and above.
The spending rules treat two categories differently. Eligible donations to Singapore charities count toward the requirement at face value. The two-times multiplier attaches to a different category. That category is grants to blended finance instruments distributed by licensed financial institutions in Singapore. The annual test of assets under management was removed for non-SFO funds, retroactive to 1 January 2025. It survives for SFO funds in recast form, tested at application and again at each financial year end.
A class licensing exemption from 15 June 2026
Separately from the tax incentives, the regulatory framework for single family offices changed on 15 June 2026. A qualifying SFO now benefits from a class exemption from fund management licensing. It is granted under the Securities and Futures regulations, in place of the case-by-case exemptions that preceded it. No individual approval is required. The conditions attached to that exemption are administrative. The office must file a notice of commencement of business with MAS within 14 days of starting operations in Singapore. The office and each of its fund vehicles must maintain an account with a bank licensed in Singapore. A foreign-incorporated vehicle may instead use a regulated bank in a jurisdiction that meets international standards. An annual return goes to MAS within four months of the financial year end, stating total assets under management and the name of the bank. No extensions are granted. Three further conditions apply. The office must be incorporated in Singapore, must serve one family only, and must keep non-family key employee shareholdings at 10% or below. Family offices already operating before 15 June 2026 have until 15 June 2027 to meet the conditions and file the notification.China's Announcement No. 21 of 2026
Announcement No. 21 of 2026 took effect on the day it was published, 24 July 2026. A State Taxation Administration announcement covering filing mechanics accompanied it. The announcement does not set a rate. It assigns trust events to two categories of income that already exist in the Individual Income Tax Law. Those are income from the transfer of property, and income from interest, dividends and bonuses. Both are taxed at 20%. The announcement creates a charge at several points. Transferring property into an offshore trust is a taxable event on the gain. Trust income is then attributed annually to a resident contributor, whether or not a distribution is made. That is the most significant departure from prior practice. Distributions to a resident beneficiary are taxed. So are deemed distributions, such as pledging trust assets against a resident's borrowing, or meeting a resident's personal expenses. A further charge arises on exit, liquidation or the death of the settlor. Income already taxed on the annual attribution is not taxed again on distribution. The look-back period runs to 1 January 2023. The announcement allows 90 days from publication to settle historic liabilities without a late payment surcharge, a window that closes on 22 October 2026.Tax residence, not nationality, sets the boundary
The announcement is drafted entirely in the statutory language of resident individual and non-resident individual. The terms Hong Kong and household registration do not appear in it. Nationality appears once, and not as a charging test. The operative question for the owner in this scenario is whether he is a mainland tax resident. That is determined by the Individual Income Tax Law and its implementing regulations, not by the announcement. A person is a mainland tax resident on one of two bases. Either he is domiciled in China, or he is present there for an aggregate of 183 days in a tax year. Domicile is defined as habitually residing in China by reason of household registration, family or economic interest relationships. Hong Kong permanent residents are treated in practice as not domiciled, on the same footing as foreign nationals, and a home return permit is a travel document that does not alter tax status. Day counting requires a full 24 hours, under a 2019 announcement of the finance ministry and the tax administration. A same-day trip to Shenzhen therefore does not add to the total. A six-year rule also applies to non-domiciled individuals. Foreign-source income paid from outside China may be exempted on filing, until the seventh consecutive year of residence at that level. A single absence of more than 30 consecutive days in any qualifying year restarts the count. Article 11 of the announcement addresses individuals who have left. It covers a person who has acquired foreign nationality, or a long-term or permanent right of residence outside the mainland. Such a person may still be determined to be a domiciled resident individual, where his principal economic interests derive from within China. Hong Kong is outside the mainland for these purposes. A Hong Kong right of abode is therefore capable of falling within that wording. No official guidance published to date addresses the point. The practical consequence is that exposure turns on the location of economic interests, not on nationality. An owner whose revenue, plants and customers are substantially mainland faces a real prospect of being treated as domiciled. An owner whose economic centre is genuinely Hong Kong or offshore does not. A narrower limb also applies to non-residents. They are taxed on contributions of mainland-situated property into offshore trusts made since 1 January 2023.What active management costs in personal tax
The section 13O and 13U exemptions apply to the fund's specified income from designated investments. They do not extend to the principal personally, and they do not extend to the management company. Those are three separate taxpayers, and the incentive reaches one of them.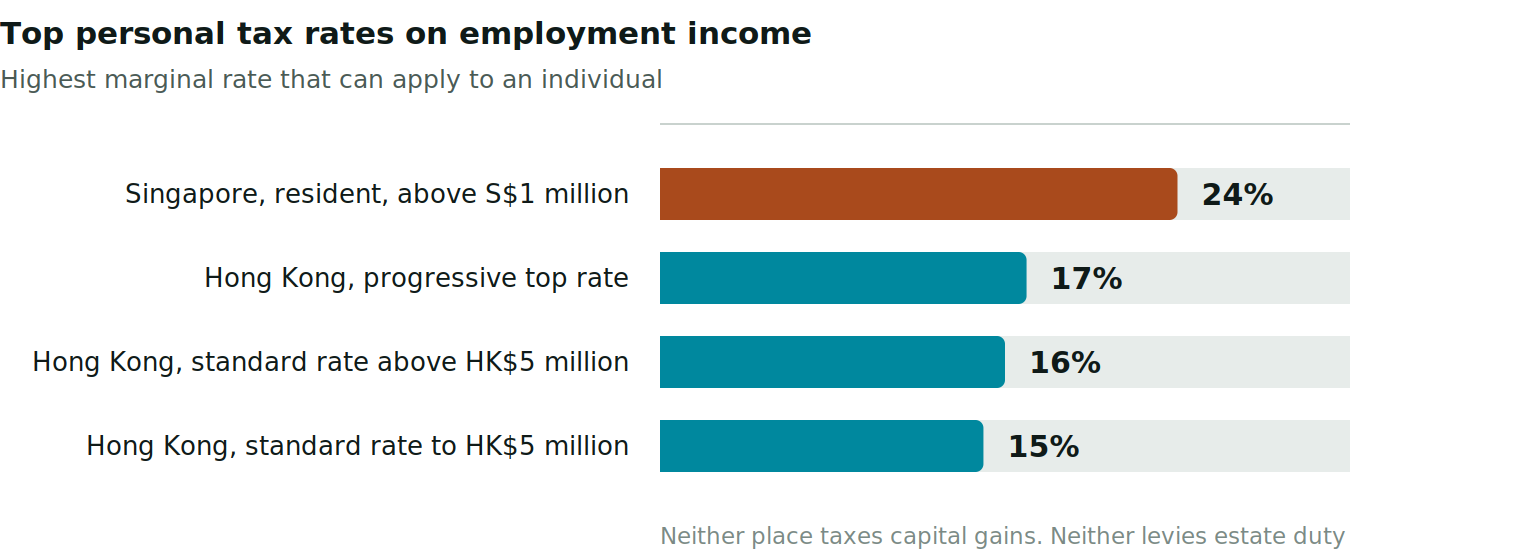 A salary drawn from the family office for work performed in Singapore is Singapore-sourced employment income. It is taxable. Resident rates run progressively to 24% on chargeable income above S$1 million. Hong Kong tops out at 17% on the progressive scale. Its standard rate is two-tiered, at 15% on the first HK$5 million of net income and 16% above that. On salary alone, Singapore is the more expensive of the two. The management company pays the 17% corporate rate on its fee income.
An employment pass is also required. In financial services the qualifying salary currently begins at S$6,200 a month at age 23 and rises with age to S$11,800 at 45 and above. Higher thresholds have been announced for new applications from 1 January 2027, at S$6,600 and S$12,700 respectively.
The other side of the comparison is larger. Singapore does not tax capital gains. The rules bringing foreign disposal gains into charge apply to entities within multinational groups, not to individuals. Foreign-sourced income received in Singapore by a resident individual has been exempt since 2004, other than income received through a partnership. Dividends from Singapore-resident companies carry no further tax under the one-tier system. Estate duty has not applied to deaths occurring on or after 15 February 2008. There is no wealth tax and no gift tax.
Hong Kong offers much of the same treatment and abolished its own estate duty in February 2006, so the gap on rates alone is narrower than commonly assumed. What distinguishes Singapore is that the fund, the manager and the substance can sit in one jurisdiction that banks, regulators and counterparties all recognise.
Presence carries a second effect. Days spent in Singapore are days not spent in the mainland. Take a principal near the 183-day threshold, or managing a six-year count. Running the office in person creates the substance the incentive requires. It also moves the day count at the same time. Substance planning and residence planning are usually treated as separate exercises. For a Hong Kong principal with mainland exposure they are one exercise.
What this means for three kinds of Hong Kong owner
For an owner whose business is substantially mainland-facing, the work to complete before 22 October 2026 is diagnostic rather than structural. The location of principal economic interests is now a question of fact under Article 11. It is established by evidence rather than by drafting. Mainland days for prior years should be counted on the full 24-hour basis, and any running six-year count identified. Contributions of mainland-situated assets to an offshore trust since 1 January 2023 fall within the narrow limb applying to non-residents. That limb has a fixed date attached to it. For an owner whose economic centre is genuinely Hong Kong or offshore, the announcement is unlikely to bite. The task is to document why, rather than to assume it. The test turns on records showing where revenue arises, where the family lives and where time is spent. Singapore then becomes a commercial decision rather than a defensive one. The 1 August 2026 changes make a modest family office materially easier to establish. The class exemption removed an approval that previously took months. And applying with one investment professional instead of two matters more to a first-time applicant than any headline rate. For an owner already holding an offshore trust, the structural question will outlast the filing deadline. A trust whose treatment depends on where its contributor and beneficiaries are resident is fragile. It is most fragile for a family spread across several countries. The residence of the next generation in ten years is a variable the current generation does not control. That favours structures whose treatment depends on where the substance sits rather than on where the people do. In practice, that means one real presence rather than three nominal ones.Our blog
Latest blog posts
Tools and strategies modern teams need to help their companies grow.