Hong Kong is widening its fund tax break and attaching conditions to it
Written by

Huan koh
Published on
October 12, 2026

Copy link
Link copied!


The bill was gazetted in June 2026, has not passed, and would apply to a year of assessment that began in April 2025. Hong Kong gazetted the Inland Revenue (Amendment) (Preferential Tax Regimes for Funds, Family-owned Investment Holding Vehicles and Carried Interest) Bill 2026 on 12 June 2026. It had its first reading on 24 June 2026. As at 11 October 2026 it has not passed. The bill sits with a committee of the Legislative Council, which met the Administration on 8 July 2026, and the Government expects it to pass during 2026. Two things about it are being reported together and should be separated. The bill genuinely widens the concession, in several directions at once. It also attaches a substance requirement and a reporting obligation to the fund exemption for the first time. It would do so for a year of assessment that began on 1 April 2025. Most coverage has described the substance test as new for family offices. It is not. Family-owned investment holding vehicles have had to meet exactly those conditions since the 2023 ordinance, and the bill relaxes how one of them is measured. The new burden lands on funds, which until now had no substance requirement at all.
What the bill widens
The clearest change is that funds with a single investor become eligible. The existing exemption has been in force since 1 April 2019. It is written around a statutory definition of a fund that requires multiple investors, which is why a fund of one has been excluded. The bill brings them in. The list of eligible assets widens by eight classes. Loans and private credit, digital assets, overseas immovable property, carbon credits and emission instruments, insurance-linked securities and equity in non-corporate private entities are all added. Precious metals come in with a 20% cap and specified commodities with a 15% volume cap. The 5% cap on incidental income is removed. That cap has been a persistent irritation, because a fund earning a small amount outside its qualifying transactions could lose the exemption on the lot. It is replaced by a list of excluded activities rather than a percentage, which is a more workable test. The treatment of special purpose entities is relaxed in the same direction.What it conditions, and on whom
The fund exemption as it stands has no economic substance requirement and no reporting mechanism at all. The bill supplies both. That is the genuinely new obligation in the package, and it falls on funds rather than on family offices. A fund that has relied on the exemption since 2019 without employing anyone in Hong Kong is the entity whose position changes. There is a real question about how it will work in practice. Advisers in Hong Kong report that it is not yet settled whether the requirements apply fund by fund. Nor is it settled whether core activities may be outsourced to a third party or an associate. The existing family office regime permits outsourcing to the eligible family office with monitoring. Whether the fund regime will do the same is expected rather than confirmed. The retrospection is the part a principal should plan around. The bill applies to years of assessment beginning on or after 1 April 2025, which is a year already more than half elapsed. The revenue department issued a transitional notice on 12 June 2026. Taxpayers may file on the basis of the proposed exemption, must monitor developments, and must write in if returns need revising once the bill passes. That is a sensible administrative answer to an awkward position, and it is also an unusual thing to ask of a taxpayer.| Condition | In force since 2023 | Under the 2026 bill | Direction |
|---|---|---|---|
| Profits tax rate on qualifying profits | 0% | 0% | Unchanged |
| Minimum assets managed | HK$240 million, measured net | HK$240 million, measured before shareholder loans | Relaxed |
| Full-time qualified employees in Hong Kong | At least two | At least two | Unchanged |
| Annual operating spending in Hong Kong | At least HK$2 million | At least HK$2 million | Unchanged |
| Family ownership | At least 95% of beneficial interest | Unchanged | Unchanged |
| Vehicles per family office | Up to fifty | Up to fifty | Unchanged |
| Income outside qualifying transactions | Capped at 5% of receipts | Cap removed, replaced by an exclusion list | Widened |
| Eligible asset classes | The 2019 schedule | Eight classes added | Widened |
| Hong Kong property income | Not addressed | New exclusion for certain property-backed shares | Tightened |
The family office conditions have been in force since 2023
The HK$240 million threshold, the two employees and the HK$2 million of annual spending all took effect under an ordinance gazetted on 19 May 2023. They have applied from the 2022-23 year of assessment. They are not a new catch. The bill changes only how the threshold is measured. Loans from shareholders and from related special purpose entities are no longer deducted, which makes it easier to clear rather than harder.
Independent confirmation that those conditions were already law arrived from an unrelated direction. From 1 March 2026 Hong Kong's investment migration scheme allows an applicant to hold qualifying investments through a private company. That company must be a family investment holding vehicle, and it must meet the same two employees, HK$2 million of spending and HK$240 million of managed assets.
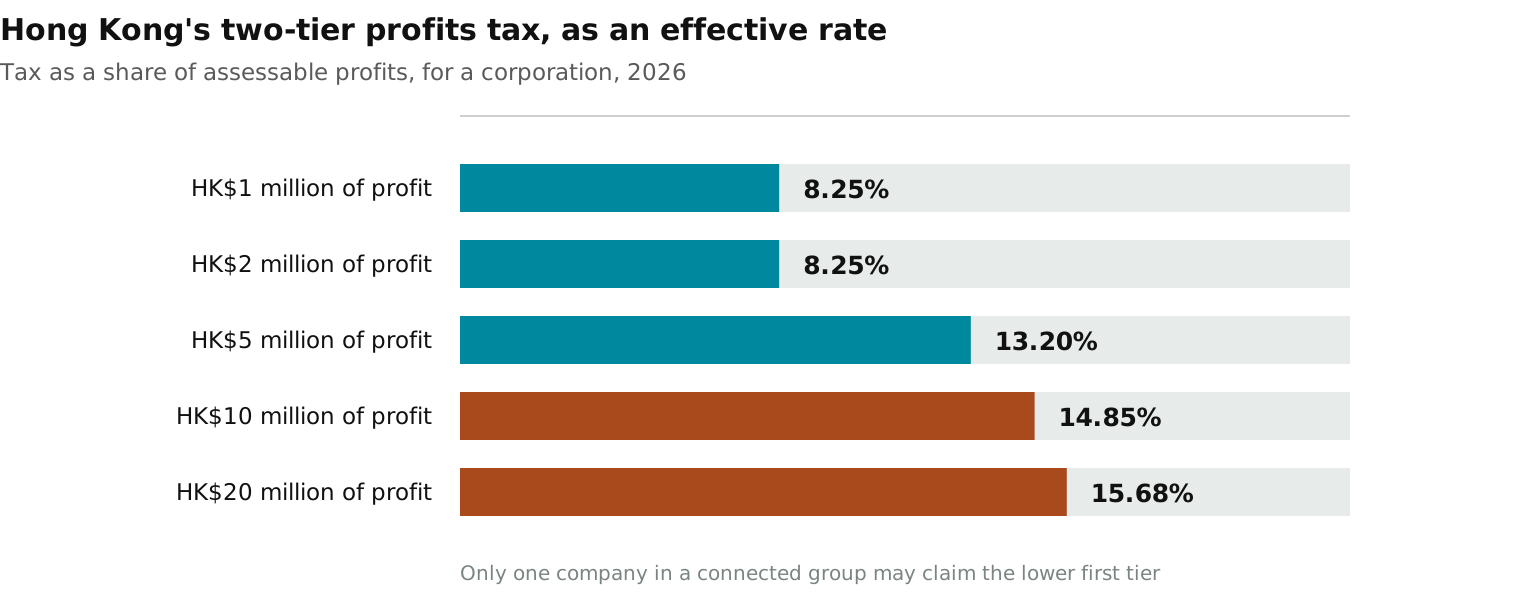
The rate itself is unchanged, and worth seeing as an effective figure rather than a headline. Hong Kong charges 8.25% on the first HK$2 million of a corporation's assessable profits and 16.5% above that. Only one company in a connected group may claim the lower tier in any year.
Singapore revised its own conditions on 31 July 2026
Singapore moved in the same window and in a different manner. The Monetary Authority issued a circular on 31 July 2026 that rewrote the conditions attaching to the fund tax incentive schemes. It split one set of rules into two, and the split corrects a confusion that has run through published commentary for years.
A fund managed by a single family office and a commercial fund managed by a third party now face materially different conditions under the same statutory provisions. The numbers most often quoted are the family office numbers, and applying them to a commercial fund overstates the entry requirement by a factor of four.
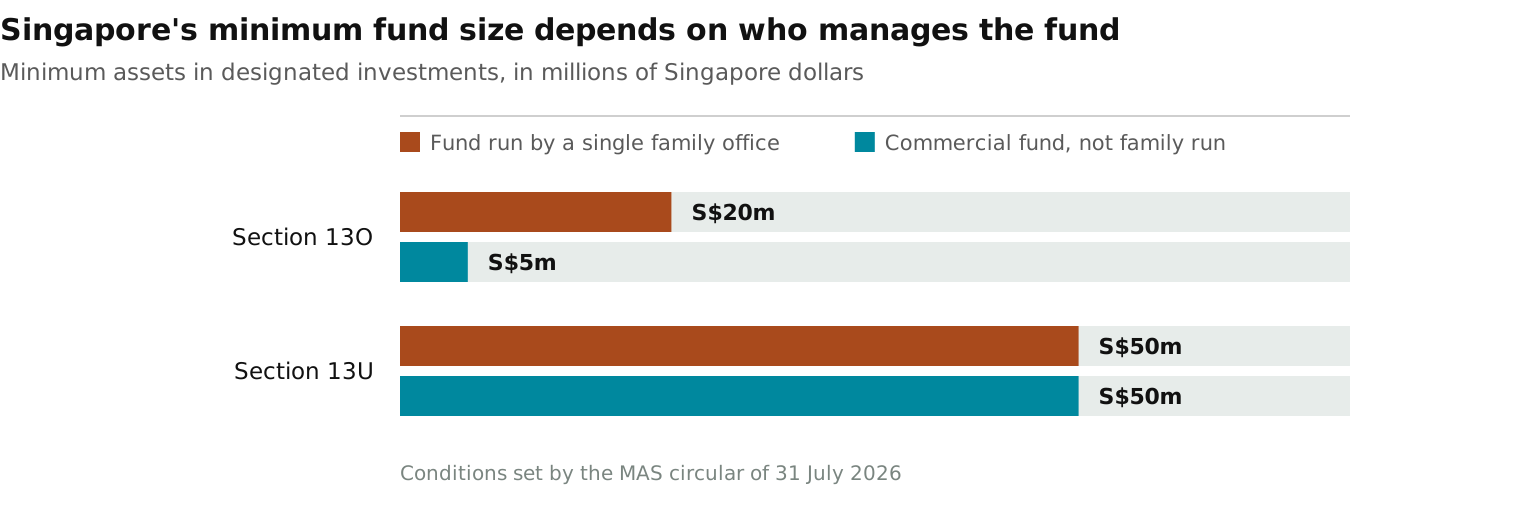
Under section 13O, a family office fund needs S$20 million of assets in designated investments at application and at the end of each period. A commercial fund needs S$5 million at application, with a grace period to the third year of assessment. Under section 13U both need S$50 million, but the surrounding conditions still differ.
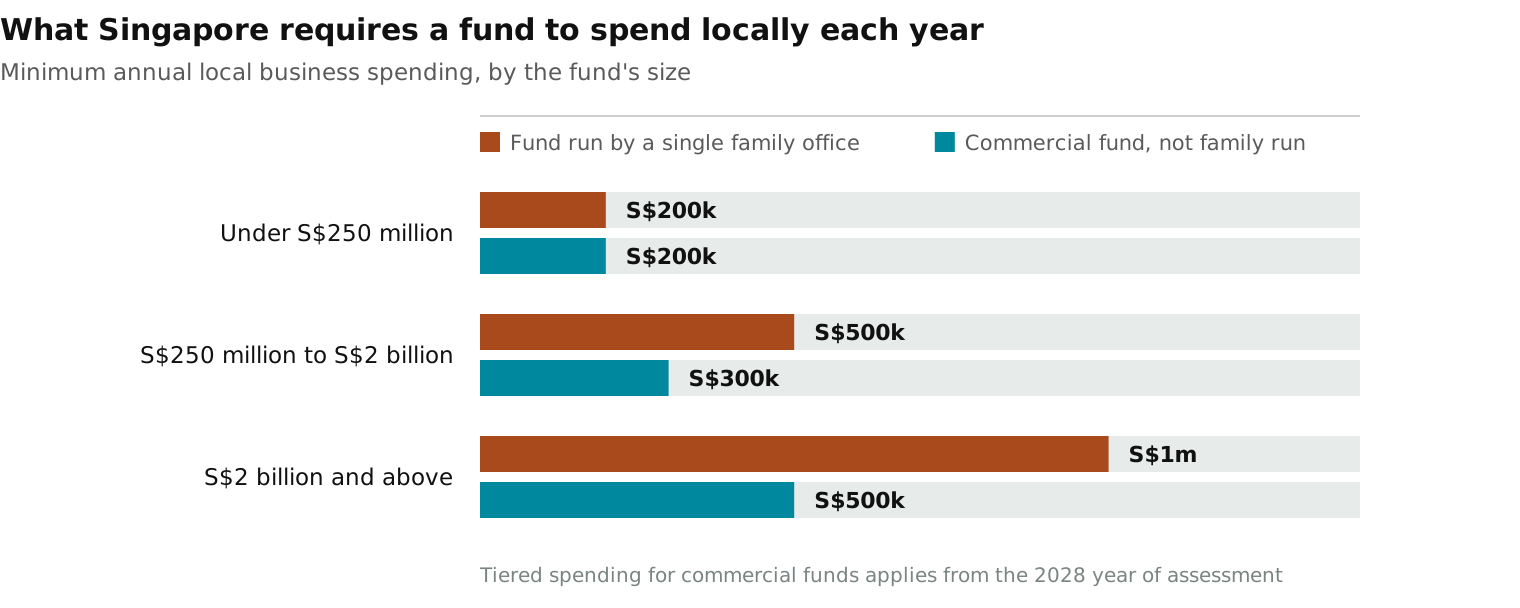
The spending requirement runs on the same size bands and different amounts. A family office fund above S$2 billion must spend S$1 million a year locally. At least S$500,000 of that must be business spending, and the remainder may be charitable donations or grants recognised at twice the amount spent. A commercial fund of the same size must spend S$500,000. Two further conditions, a capital deployment requirement and a private banking account, apply to the family office track only.
Singapore is not immune to mid-stream change either
The comparison usually drawn is that Singapore publishes its conditions in advance and does not change them afterwards. The first half of that is defensible. The second half is not, and a reader who follows this closely will know it. Overstating the point is the fastest way to lose an audience that checks.
Three things in the 31 July 2026 circular cut against the claim. The removal of the annual asset maintenance test for commercial funds was made retroactive to 1 January 2025, nineteen months earlier. Family office funds holding awards granted under three earlier sets of conditions were moved onto the new ones, including the higher spending tiers and the banking requirement. And a commercial fund that fails to reach S$5 million by its third year of assessment has its award revoked from the date it started. That reopens years already filed.
The honest version of the comparison is narrower and still favours Singapore. Conditions arrive by dated circular, effective dates are generally prospective, and several of the tightening measures were deferred to the 2028 year of assessment. Hong Kong is legislating in June 2026 for a year that began in April 2025. The difference is in the orderliness of the process rather than in an absolute rule that one country never reaches backwards.
One asymmetry should also be acknowledged. Almost everything Hong Kong is doing retrospectively is in the taxpayer's favour. Wider assets, a removed cap and a relaxed measurement all help. The only genuinely new burden being applied to a year already running is the substance and reporting requirement on funds.
Hong Kong is competing hard, and Singapore has said so
An article that presents Singapore's position as unchallenged would be contradicted by Singapore's own regulator. On 28 July 2026 the Managing Director of the Monetary Authority said it was in discussions with the industry about improving competitiveness. He named competition from places like Hong Kong. That is the regulator naming the pressure.
The pressure is real and funded. A study by Deloitte for Hong Kong's investment promotion agency was published on 10 February 2026. It counted 3,384 single family offices operating in Hong Kong. Their direct operating spending was put at about HK$12.6 billion a year, employing more than 10,000 full-time professionals. The Government has set a target of helping more than 220 family offices establish or expand between 2026 and 2028.
Those counts are not comparable with Singapore's. Hong Kong does not require a family office to register, so the 3,384 figure is an estimate of the whole population. Singapore reports more than 2,000 single family offices as at the end of 2025, but counts only those that have been awarded tax incentives. Offices operating in Singapore without an award are not in the number. One figure is an estimate of everything and the other is a floor.
Where the money actually sits
The assets under management figure is the one that compares cleanly between the two centres. It is published by the regulator rather than estimated by a consultancy, and it is measured the same way each year.
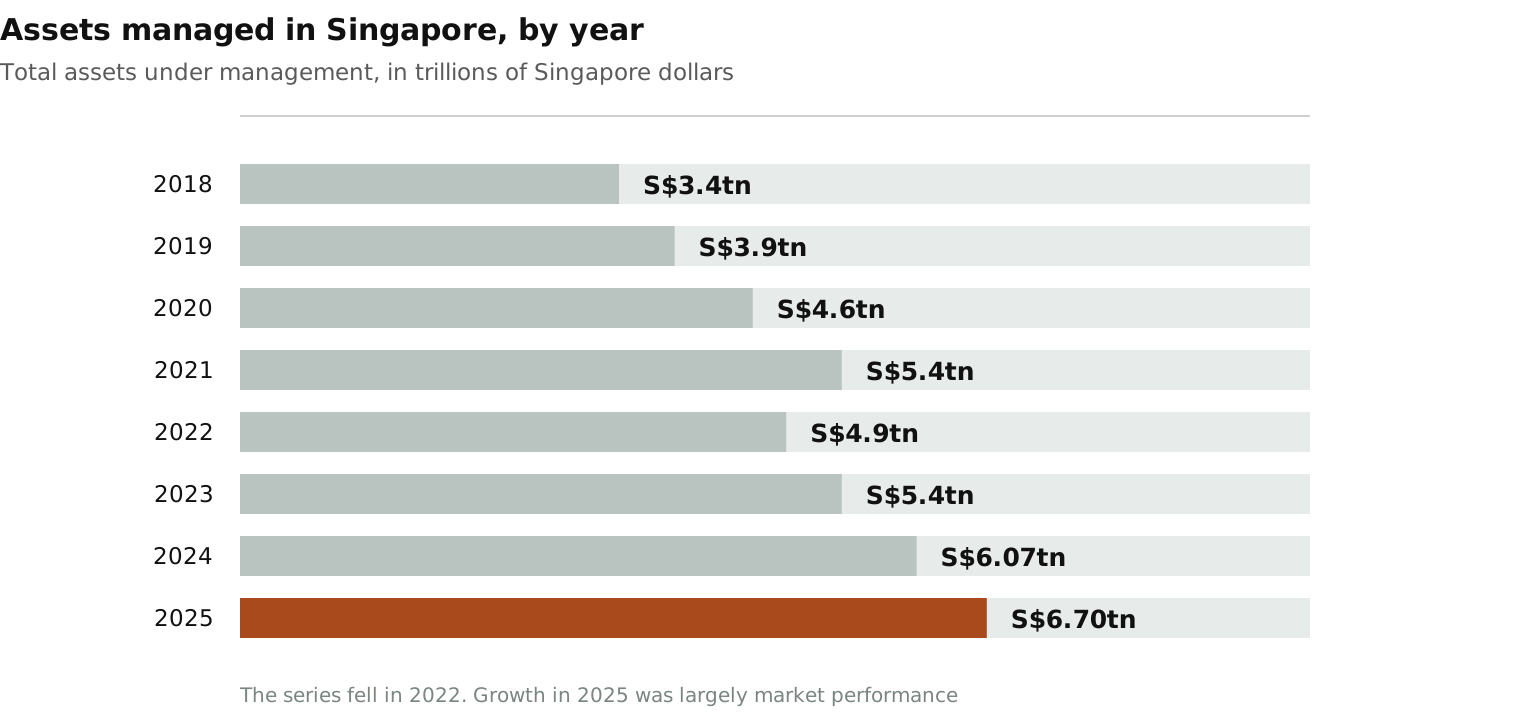
Singapore's industry held S$6.7 trillion at the end of 2025, up 10.1% on the year, with net inflows of S$376 billion. Three quarters of that money is sourced from outside Singapore and about 88% of it is invested outside Singapore. The industry is a place where international money is managed rather than a pool of domestic savings.
Two details stop that being a victory lap. The growth was driven largely by market performance rather than by new mandates, and the alternatives picture was weak. Alternative assets grew 0.4%, private equity and venture capital grew 1%, and real estate fell 16%. The number of licensed managers rose under 2% against 10% asset growth, which is not the pattern of an industry adding firms.
What this means for families already in Hong Kong, families choosing now, and advisers with clients in both
For a family office already established in Hong Kong, the near-term question is a filing question rather than a structural one. The revenue department has invited taxpayers to file the 2025-26 year on the basis of the proposed exemption and to correct afterwards if the bill changes. That is workable, but a position taken now may have to be revisited. The file should record the basis on which the return was prepared. The substance conditions that apply to a family investment holding vehicle have not changed since 2023.
For a family choosing between the two now, the decision has stopped being about the headline rate. It is about which set of conditions the family can actually meet and sustain. Hong Kong asks for two employees, HK$2 million of local spending and HK$240 million under management. Singapore asks for a fund of S$20 million and two investment professionals, one of whom is not family. It also asks for local spending from S$200,000, a capital deployment requirement and a private banking account. Those are different shapes of commitment, and the right answer depends on where the family's people and investments already are.
For an adviser with clients on both sides, the useful discipline is to date every condition. Hong Kong's family office conditions date from 2023 and are being relaxed. Its fund substance requirement is proposed and would be retrospective. Singapore's revised conditions date from 31 July 2026, with some elements deferred to 2028 and one made retroactive to the start of 2025. A client who is told only the current state of the rules, without the dates they arrived and the dates they bite, cannot plan around either country.
Our blog
Latest blog posts
Tools and strategies modern teams need to help their companies grow.