Vietnam’s index upgrade drew US$54 million of buying against forecasts of billions
Written by

Huan koh
Published on
September 22, 2026

Copy link
Link copied!


Projected flows and measured flows are different things, and the gap is worth understanding before the next upgrade.
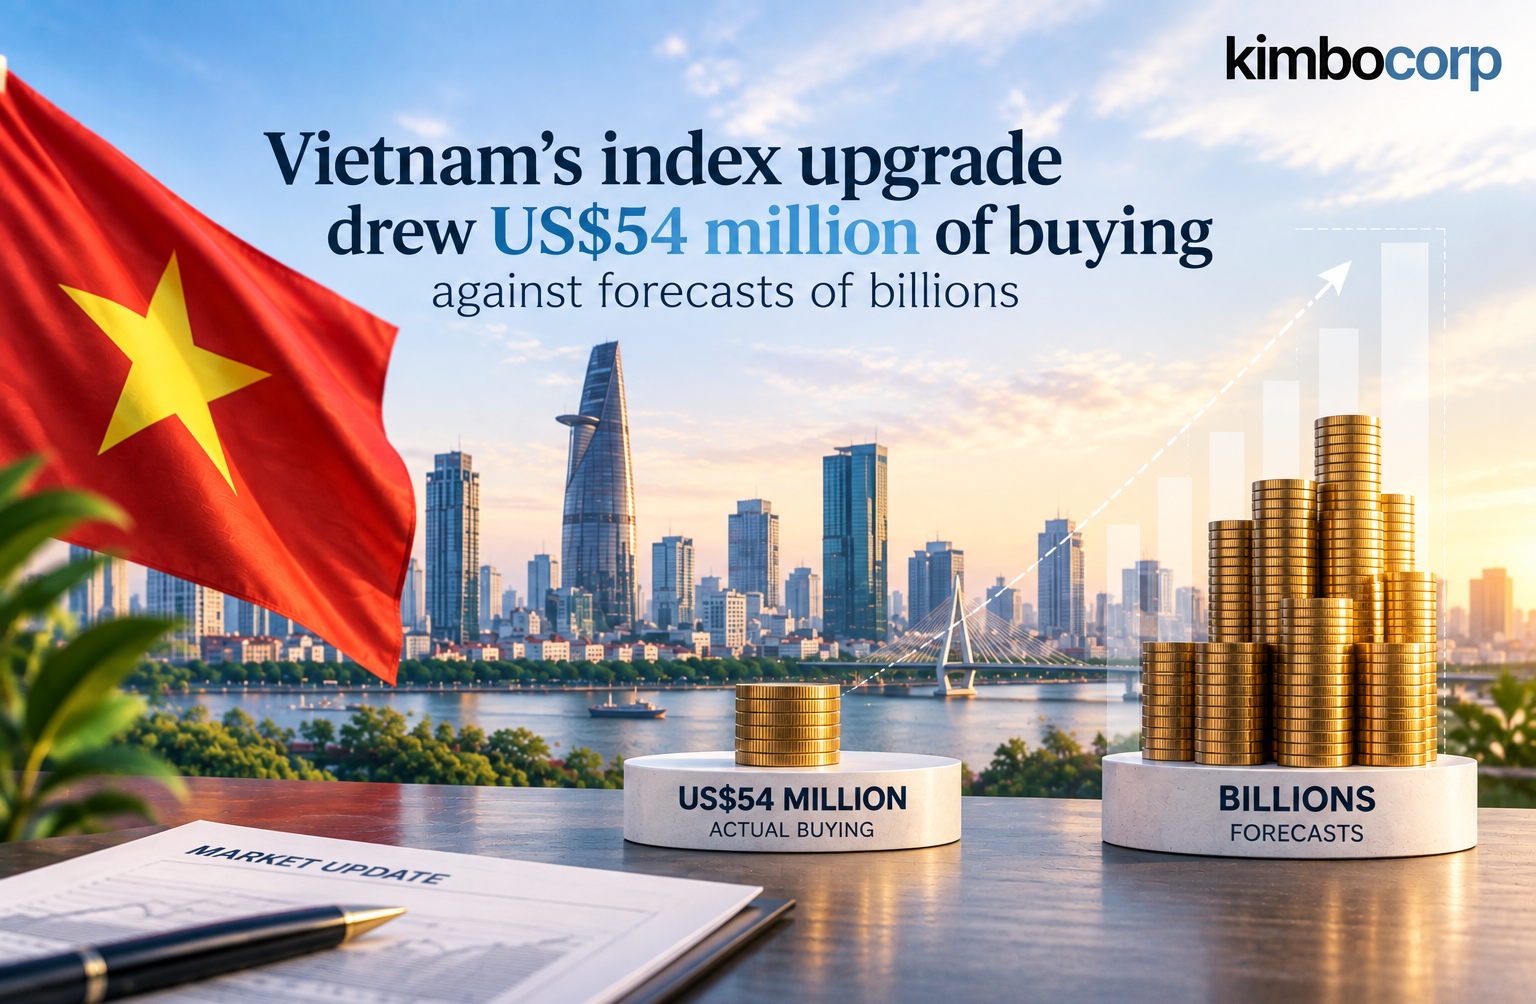
FTSE Russell reclassified Vietnam from Frontier to Secondary Emerging with effect from 21 September 2026. The change adds 27 Vietnamese stocks to its All-Cap index and six to its All-World index. Brokerages forecast inflows of between US$1.5 billion and US$4.4 billion. In the week to 18 September 2026, the last full week before the change took effect, foreign investors bought a net US$54.2 million of Vietnamese equities, according to Bloomberg. That was the largest weekly tally in about six weeks.
An index reclassification is the cleanest capital markets event available for this kind of comparison. The date is fixed well in advance. The constituent list is published. The buying by index-tracking funds is mechanical rather than discretionary. If forecasts and outcomes diverge this far under those conditions, they diverge further in every messier situation, which includes most private fundraising.
Foreign selling shrank to almost nothing before the upgrade
The more useful series is not the week of buying but the five months before it. Foreign investors were net sellers of Vietnamese equities in every month from May 2026. The scale of that selling then collapsed as the upgrade approached. The pattern is what a market looks like when it stops losing money rather than when it starts gaining it.
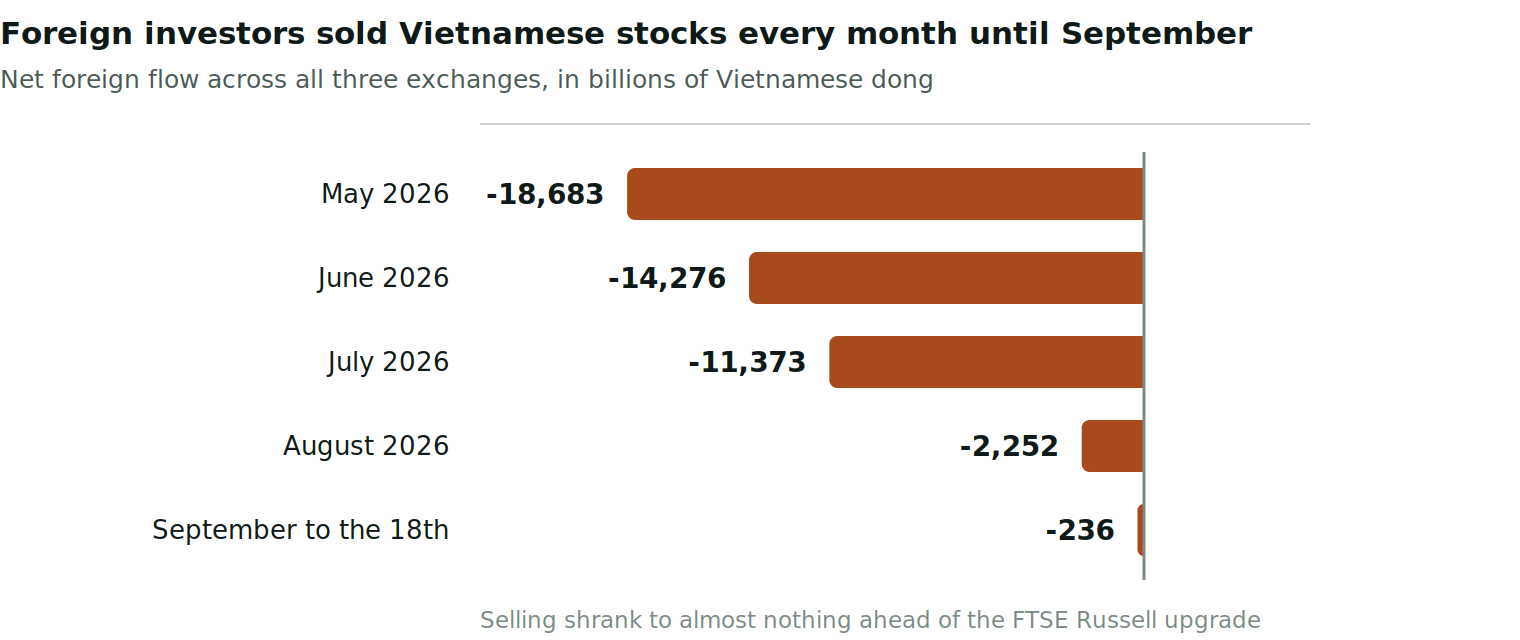
Net selling ran at 18,683 billion dong in May 2026. It fell to 14,276 billion in June 2026, 11,373 billion in July 2026 and 2,252 billion in August 2026. September 2026 to the 18th was still net negative, at 236 billion dong. Foreign investors have taken US$3.5 billion out of the market so far in 2026, after US$4.8 billion in the whole of 2025. Three consecutive net-buying sessions from 16 to 18 September 2026 totalled about 3,006 billion dong. On 18 September 2026 alone, 21 of the 27 stocks in the FTSE basket were net bought, worth 1,717 billion dong.
The reclassification did not reverse a year of selling. It stopped it. That is a smaller claim than the forecasts implied, and a more accurate description of what index inclusion does in practice. Inclusion changes who is obliged to hold a market. It does not by itself change what discretionary investors think of it, and the discretionary money is the larger pool.
What was forecast and what was measured
The forecasts published before the event span a wide range. They also measure different things from each other, which is part of why the range is so wide. Some estimate mechanical index buying, some estimate total foreign appetite, and one is a single firm describing its own intention.
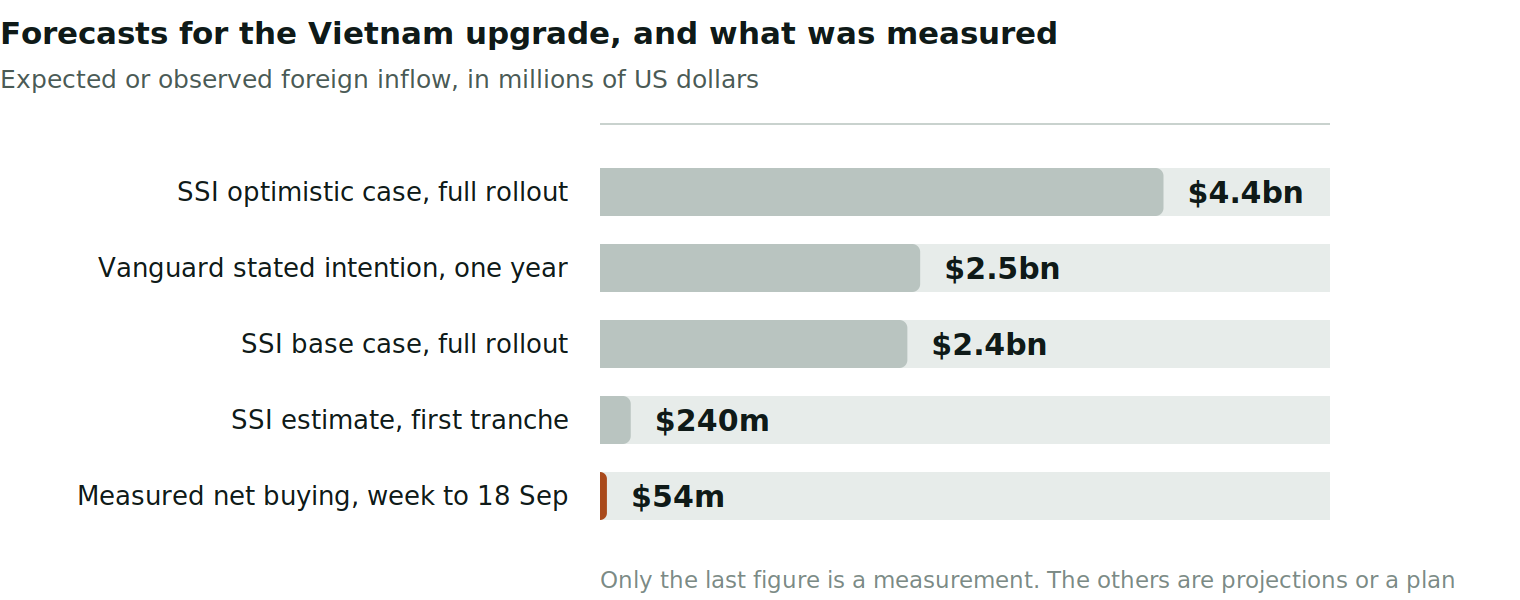
SSI Securities estimated about US$240 million of passive net purchases in the first tranche. Its base case for the full implementation was about US$2.4 billion, with an optimistic case above US$4.4 billion. Vanguard's head of investment management for Asia Pacific said on 18 September 2026 that the firm expects to invest US$2.5 billion in Vietnamese equities over the following year. Only the US$54.2 million is a measurement. The others are projections, or in Vanguard's case a stated intention that has not yet been executed.
Two cautions apply to the measurement itself. Vietnamese exchange data for the three sessions to 18 September 2026 imply a larger figure than the weekly dollar total. That points to a different venue scope or cut-off between the two sources, and both should be quoted with their source attached. The full implementation is also phased across several tranches into 2027, so a single week measures the first instalment rather than the total. The honest reading is that the early evidence sits at the low end of the forecast range.
Southeast Asian startup funding rebounded to US$1.34 billion in August 2026
The private markets in the region moved over the same period, and the monthly series continues to swing violently. Three consecutive months have produced three completely different pictures of the same market. Each of them was reported as a trend at the time.
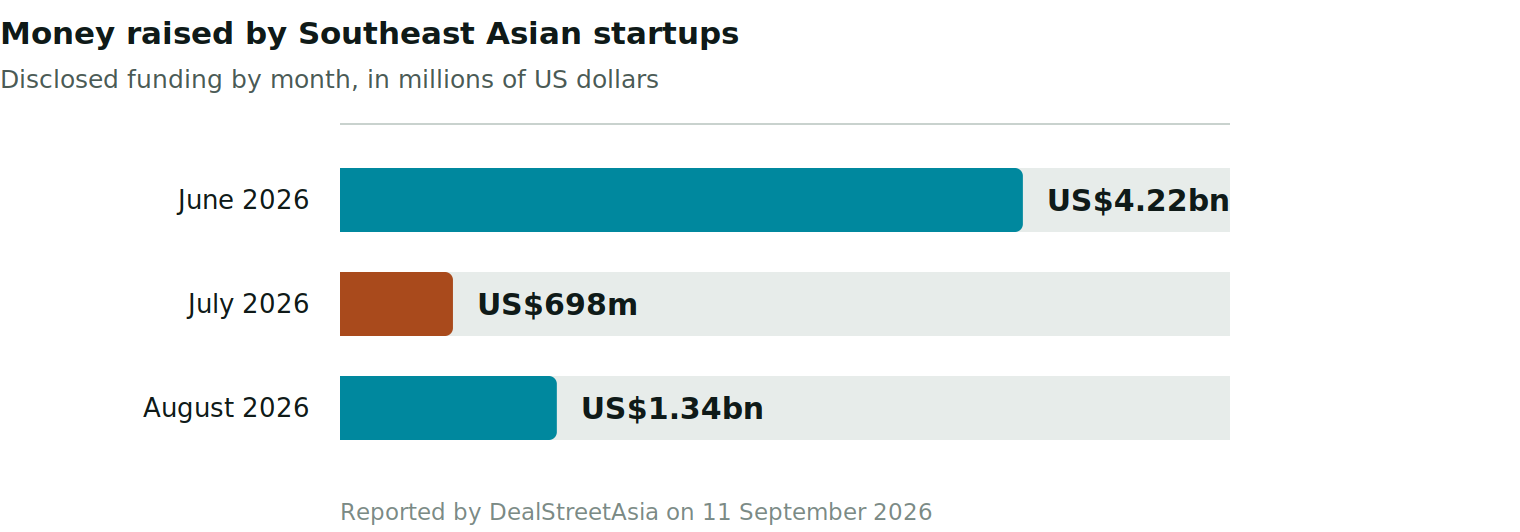
Startups in the region raised about US$1.34 billion in August 2026. That compares with roughly US$698 million in July 2026 and US$4.22 billion in June 2026. The three months vary by a factor of six. A founder benchmarking a raise against any one of them is using a number that will not describe the following month, and did not describe the preceding one either.
Four deals took 87% of the August total
The composition is the part that decides whether the rebound is relevant to any particular company. A total is made up of transactions, and transactions have sizes. When a few of them are very large, the total stops describing the typical case.
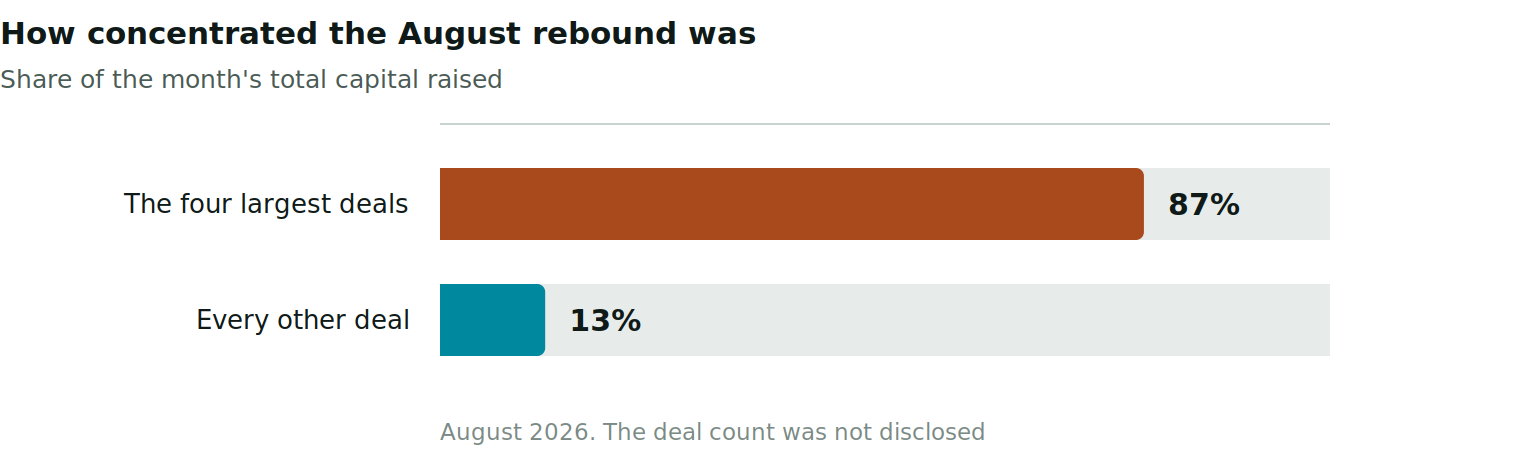
Four megadeals accounted for about 87% of the August 2026 total. Every other transaction in the region shared the remaining 13%. On a US$1.34 billion total, that is about US$174 million. That smaller figure is the pool from which an ordinary round is funded. It is the same pattern recorded in June 2026, when five deals took 93% of a much larger month. It is also the pattern visible in the region's artificial intelligence funding across 2026.
One signal from outside the region is worth noting for anyone considering private credit as an alternative to equity. Morgan Stanley capped withdrawals from its North Haven Private Income Fund for a third consecutive quarter on 18 September 2026. Investors tendered 11.4% of shares against a 5% repurchase limit, with an expected effect on net asset value of about US$101 million. That is a United States wealth-management vehicle rather than an Asian one, and it says nothing directly about Asian credit supply. It does indicate that retail appetite for non-traded private credit is being tested, and vehicles of that kind are part of what ultimately funds credit managers in this region.
What this means for companies weighing a listing, founders raising now, and anyone quoting a forecast
For a company weighing a listing or an index-driven strategy, the Vietnam sequence is the best available evidence on what reclassification delivers. It stopped a run of selling that had lasted five months. It produced modest buying in the week before the effective date. It did not produce billions in a week, and the remaining tranches run into 2027. A business planning around a valuation uplift from index flows should build on the first-tranche estimate rather than the full-rollout case. The first tranche is the only part that has now been partly observed.
For a founder raising in Southeast Asia, the August 2026 rebound does not change the arithmetic. The relevant number is the 13% that was not taken by four deals, which works out at roughly US$174 million across every other company in the region for the month. Three months at US$4.22 billion, US$698 million and US$1.34 billion describe a market whose monthly totals are set by a handful of transactions. Plan on the deal count and the size distribution instead, and treat the monthly headline as noise.
For anyone quoting a forecast in a board paper or an investment memorandum, this episode is a clean test case. A brokerage range of US$1.5 billion to US$4.4 billion was published for an event with a fixed date, a published constituent list and mechanical buying. The first measurable week came in at US$54.2 million. Forecasts of this kind are estimates of a mechanical maximum, not predictions of behaviour, and they should be labelled as such wherever they appear. The figure that survives scrutiny is always the one with a measurement date attached to it.
Our blog
Latest blog posts
Tools and strategies modern teams need to help their companies grow.